Coreintegra Consulting IPO Listing: Listing Price, Performance and Review
Staffing, payroll outsourcing and labour law compliance company with HR-tech and reg-tech tools, serving 600+ clients and managing over 12,000 associates.
A flat debut for a large-revenue, wafer-thin-margin staffing firm. Steady but unexciting.
Our own view, not investment advice.
Subscription by category
Final subscription, 25 Sep 2026, 6:54 PM
Listing day, 30 Sep
NSE SME prices
| Issue price | ₹78.00 |
| Open | ₹78.10 |
| High | ₹79.50 |
| Low | ₹74.20 |
| Close | ₹78.90 |
| Gain at close | +1.2% |
IPO timeline
Coreintegra Consulting Services had a flat debut. The ₹21.99 crore NSE SME issue, priced at ₹78, opened at ₹78.10 on 30 September, dipped to ₹74.20 and closed at ₹78.90, up 1.2%.
The staffing and HR compliance company had drawn only 1.40 times subscription, so a muted listing was in line with expectations.
How Coreintegra Consulting Services listed
| Detail | Value |
|---|---|
| Issue price | ₹78 |
| Listing price (NSE SME) | ₹78.10 (+0.1%) |
| Day’s high | ₹79.50 |
| Day’s low | ₹74.20 |
| Listing day close | ₹78.90 (+1.2%) |
The narrow trading range shows little excitement either way. The next trading session after the 2 October holiday is on Monday 5 October.
Coreintegra Consulting Services IPO at a glance
| Detail | Coreintegra Consulting Services IPO |
|---|---|
| Issue size | ₹21.99 crore (28,19,200 shares) |
| Issue price | ₹78 per share (face value ₹10) |
| Lot size | 1,600 shares |
| Individual investor minimum | 2 lots, 3,200 shares (₹2,49,600) |
| Anchor round | None |
| Bidding dates | 23 Sep to 25 Sep 2026 |
| Allotment | 28 Sep 2026 |
| Listing | 30 Sep 2026 on NSE SME |
| Promoter holding | 93.04% before, 68.03% after |
| Lead manager | Marwadi Chandarana Intermediaries |
| Registrar | Purva Sharegistry |
| Market maker | Rikhav Securities |
What Coreintegra Consulting Services actually does
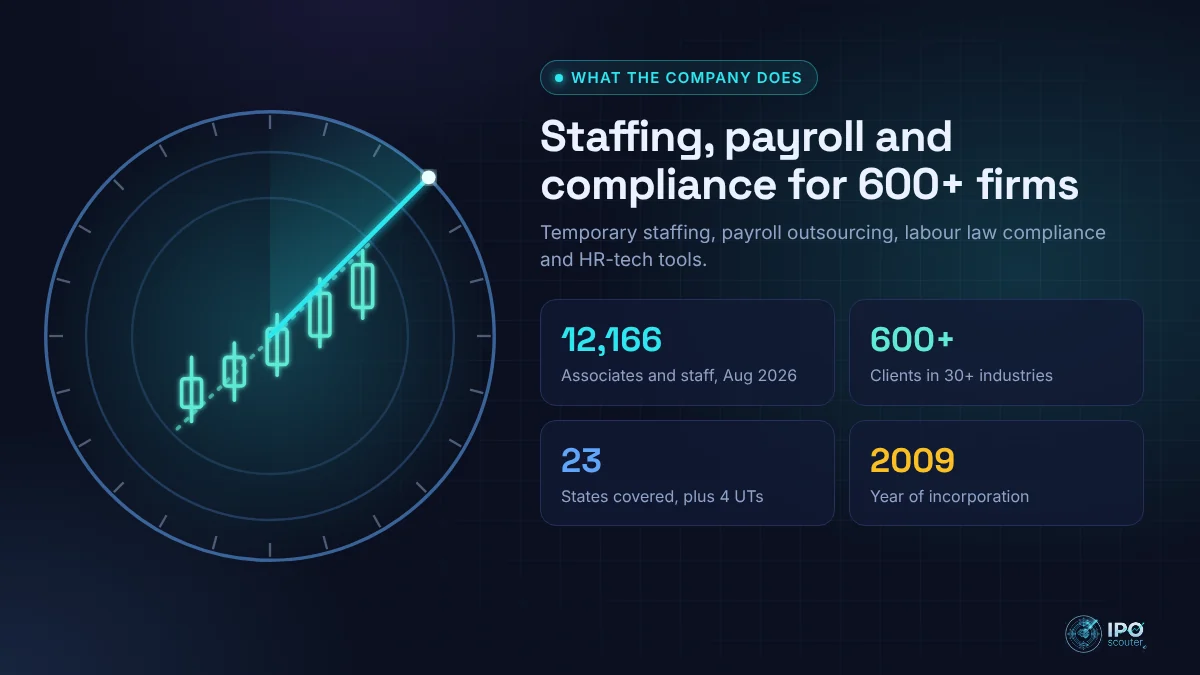
Coreintegra Consulting Services Ltd was incorporated in 2009 and is promoted by Sriram Natarajan, Sangeetha Sriram and Gaurav Bali. It provides staffing, payroll outsourcing, labour law compliance, HR advisory and vendor management, plus HR-tech (CoreX, Core Pay) and reg-tech (Ctrl-F, Core-PFT) tools.
It serves more than 600 clients across over 30 industries and 1,500 client locations, through seven branches covering 23 states and four union territories. Including associates deployed at clients, its workforce was 12,166 in August 2026.
The IPO funds IT infrastructure (₹11.76 crore), leadership hiring (₹5.75 crore) and brand building.
The numbers behind the business
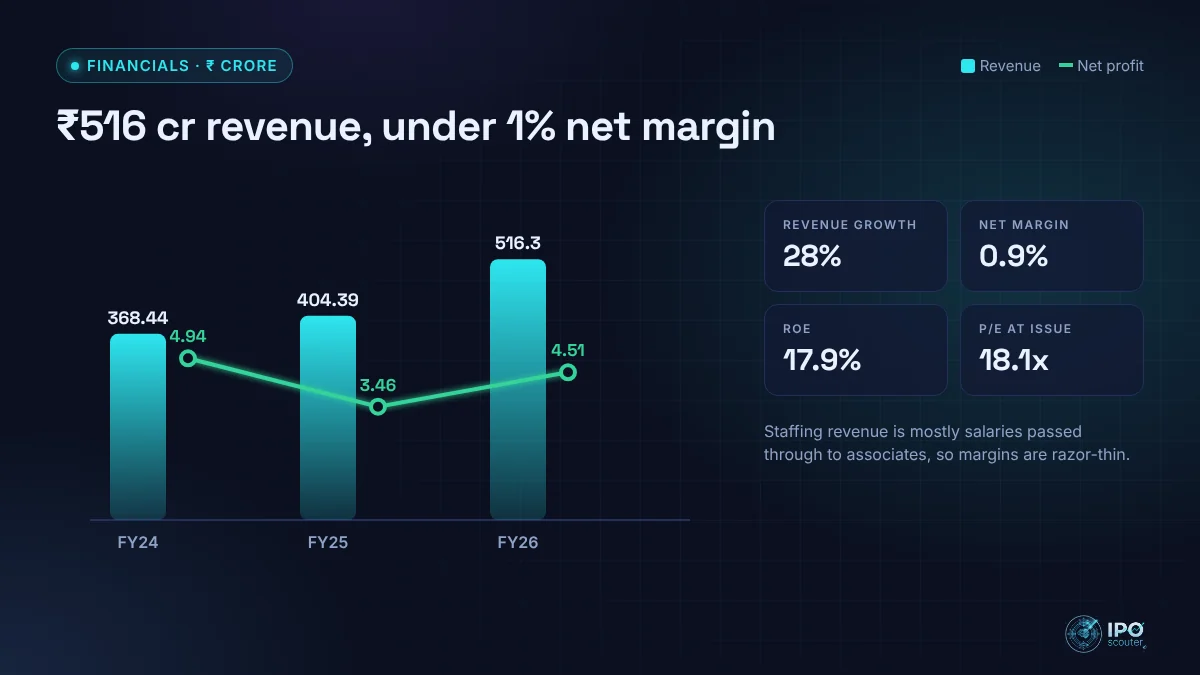
Here are the figures from the offer documents, in ₹ crore, as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 368.44 | 404.39 | 516.3 |
| EBITDA | 5.81 | 4.2 | 6.01 |
| Net profit | 4.94 | 3.46 | 4.51 |
| Net worth | 19.43 | 22.89 | 27.41 |
| Total assets | 49.96 | 56.8 | 68.51 |
What these numbers tell us, in plain language:
- Large revenue, small profit. Revenue rose from ₹368 crore in FY24 to ₹516 crore in FY26, but profit was only ₹4.5 crore in FY26, below FY24’s ₹4.9 crore.
- Razor-thin margins. EBITDA margin was 1.2% and net margin 0.9%. In staffing, most revenue is associates’ salaries passed through to clients.
- Modest returns. ROE was about 18%.
- Valuation. Post-issue P/E was about 18x at the issue price.
How the subscription ended
| Category | Final (25 Sep) |
|---|---|
| QIB | 1.05x |
| NII | 1.46x |
| Retail | 1.42x |
| Total | 1.40x |
There was no anchor book. By the close on 25 September, QIBs had bid 1.05 times, NIIs 1.46 times and retail 1.42 times, for 1.40 times overall across 657 applications.
What to weigh now
Margins are the whole story
With net margins under 1%, small changes in wage costs, statutory contributions or client pricing can wipe out profit. India’s new labour codes add both opportunity and compliance cost.
Can tech lift margins?
The IPO invests in HR-tech and reg-tech platforms. If those products gain traction, they could add higher-margin revenue on top of the staffing base.
Strengths and risks
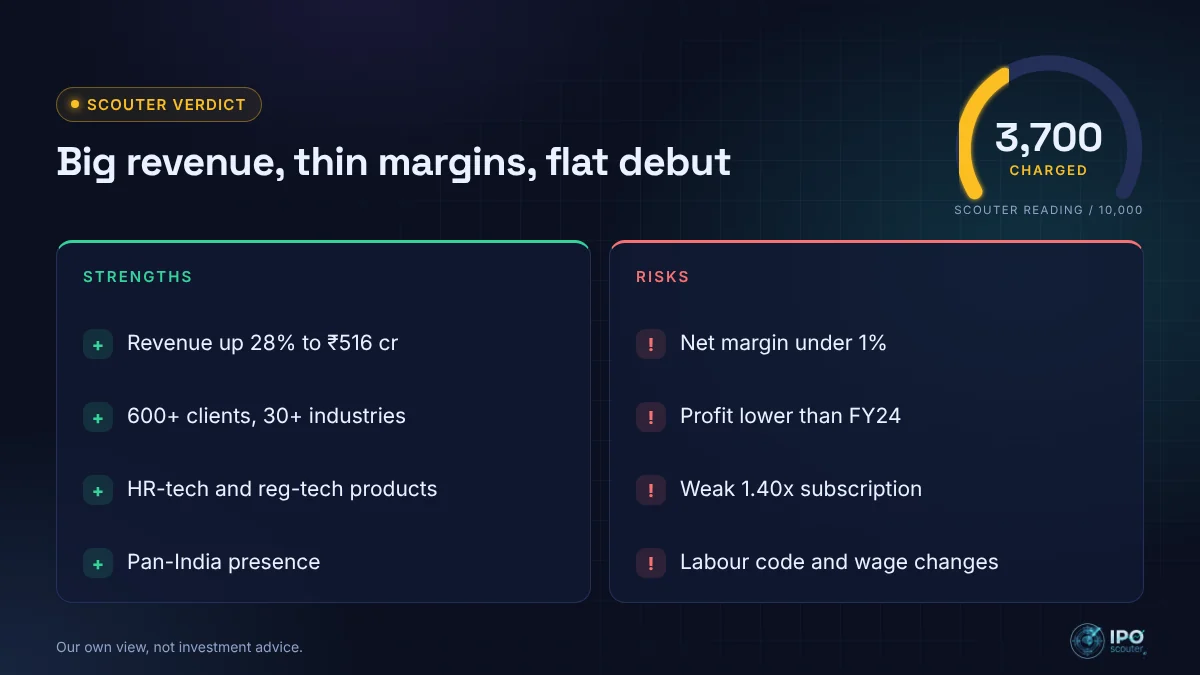
Strengths
- Revenue up 28% to ₹516 crore in FY26
- 600+ clients across 30+ industries
- Pan-India presence across 23 states
- HR-tech and reg-tech products
- Closed slightly above the issue price
Risks
- Net margin under 1%
- FY26 profit below FY24 level
- Weak 1.40 times subscription
- Exposure to labour code and wage changes
- Thin SME liquidity
Scouter verdict: A large but very low-margin staffing business whose flat debut reflects limited investor interest. The tech investments are the main upside to watch. This is our own view, not investment advice.
What to watch from here
- Trading on 5 October
- Margin trends and HR-tech revenue
- Impact of labour code implementation
Coreintegra Consulting Services IPO: frequently asked questions
Coreintegra listed at ₹78.10 on NSE SME on 30 September 2026, against an issue price of ₹78.
The stock closed at ₹78.90, up 1.2% from the issue price.
It was subscribed 1.40 times overall, with QIB at 1.05x, NII at 1.46x and retail at 1.42x.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 1 October 2026 (2 October was a market holiday).
On this page
Key valuation
| Listing gain (close) | +1.2% |
| P/E at issue (post) | 18.1x |
| Net margin | 0.9% |
| EBITDA margin | 1.2% |
| ROE | 17.9% |
| Anchor money | Nil |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon