Peshwa Wheat IPO: Listing Price, Performance and Review
Indore-based wheat flour mill producing atta, sortex wheat, besan and maize flour in bulk packs for distributors across Madhya Pradesh, Maharashtra, Karnataka and Gujarat.
Fast growth and a low P/E could not overcome weak HNI demand and a thin-margin commodity business. The stock hit the lower circuit on day one.
Our own view, not investment advice.
Subscription by category
Final subscription, 28 Sep 2026, 6:54 PM
Listing day, 1 Oct
BSE SME prices
| Issue price | ₹101.00 |
| Open | ₹100.05 |
| High | ₹100.05 |
| Low | ₹95.05 |
| Close | ₹95.05 |
| Loss at close | -5.9% |
IPO timeline
Peshwa Wheat’s debut was disappointing. The ₹53.52 crore fixed-price issue at ₹101 opened at ₹100.05 on BSE SME on 1 October and slid straight to the 5% lower circuit, closing at ₹95.05, down 5.9%.
The flour miller’s headline 2.77 times subscription was misleading: the tiny QIB portion was bid 177 times, but big HNIs bid only 0.16 times and retail 1.72 times.
How Peshwa Wheat listed
| Detail | Value |
|---|---|
| Issue price | ₹101 |
| Listing price (BSE SME) | ₹100.05 (-0.9%) |
| Day’s high | ₹100.05 |
| Day’s low | ₹95.05 |
| Listing day close | ₹95.05 (-5.9%) |
The stock never traded above its opening price, which means there was little buying interest once trading began. The next trading session after the 2 October holiday is on Monday 5 October.
Peshwa Wheat IPO at a glance
| Detail | Peshwa Wheat IPO |
|---|---|
| Issue size | ₹53.52 crore (52.99 lakh shares, entirely fresh issue) |
| Issue price | ₹101 per share (face value ₹10) |
| Lot size | 1,200 shares |
| Individual investor minimum | 2 lots, 2,400 shares (₹2,42,400) |
| Quota | Retail 50.02%, NII 48.99%, QIB 0.98% |
| Anchor round | None |
| Bidding dates | 24 Sep to 28 Sep 2026 |
| Allotment | 29 Sep 2026 |
| Listing | 1 Oct 2026 on BSE SME |
| Promoter holding | 72.61% before, 52.39% after |
| Lead manager | Finaax Capital Advisors |
| Registrar | Maashitla Securities |
| Market maker | Bhansali Value Creations |
What Peshwa Wheat actually does
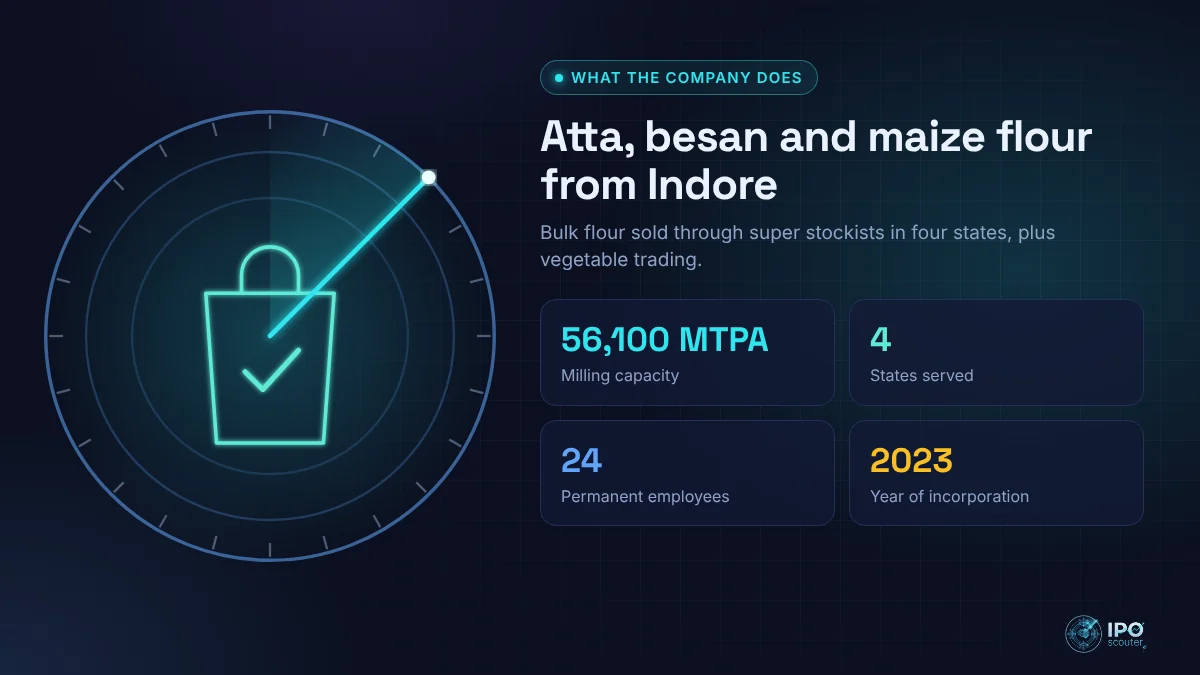
Peshwa Wheat Ltd was incorporated in 2023. It processes wheat into atta, sortex wheat, besan and maize flour at an integrated unit in Indore with 56,100 tonnes a year of capacity, sold in 50 kg and 30 kg packs through super stockists in Madhya Pradesh, Maharashtra, Karnataka and Gujarat. It also trades vegetables. It had 24 permanent employees.
The IPO funds plant and machinery (₹6.69 crore), civil construction (₹5.01 crore) and working capital (₹26.50 crore).
The numbers behind the business
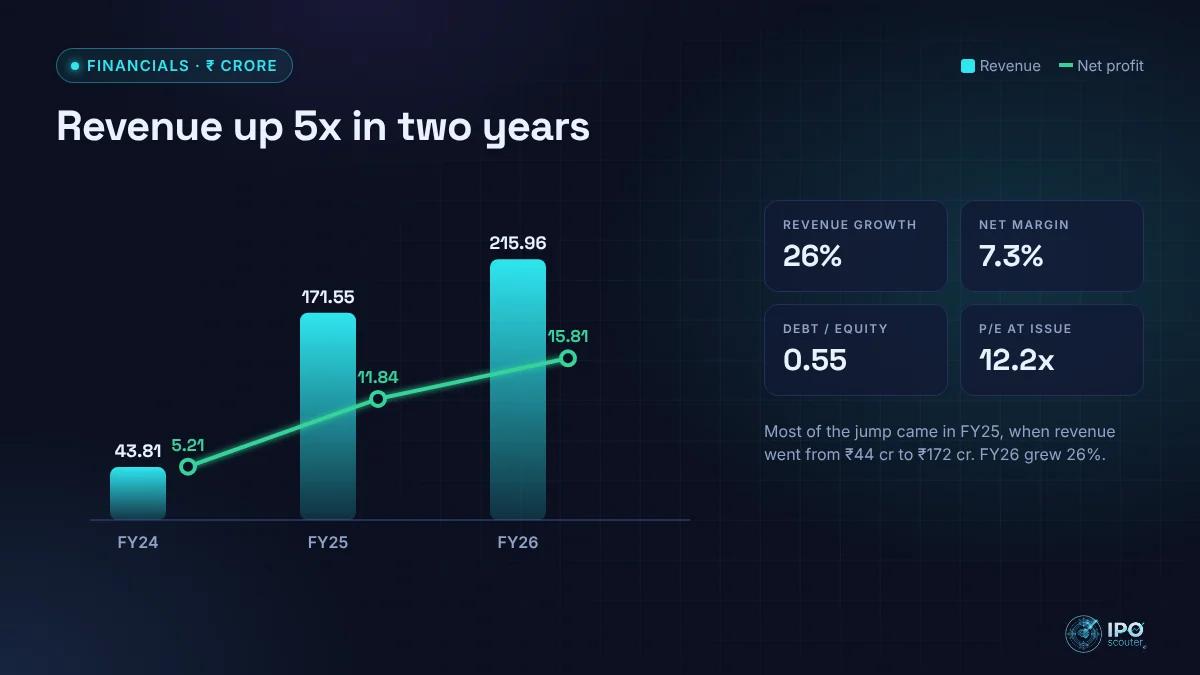
Here are the figures from the offer documents, in ₹ crore, as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 43.81 | 171.55 | 215.96 |
| EBITDA | 6.91 | 18.05 | 22.73 |
| Net profit | 5.21 | 11.84 | 15.81 |
| Net worth | 15.42 | 27.26 | 43.06 |
| Borrowings | 7.93 | 22.6 | 23.74 |
| Total assets | 31.17 | 65.95 | 80.6 |
What these numbers tell us, in plain language:
- Explosive growth from a new base. Revenue went from ₹43.8 crore in FY24 to ₹171.6 crore in FY25 and ₹216 crore in FY26. Profit grew from ₹5.2 crore to ₹15.8 crore.
- Margins are thin, as expected. EBITDA margin was 10.5% and net margin 7.3% in FY26.
- Moderate debt. Borrowings were ₹23.7 crore, debt to equity 0.55.
- Valuation looked cheap. Post-issue P/E was about 12.2x at the issue price, which did not stop the stock from falling on day one.
How the subscription ended
| Category | Final (28 Sep) |
|---|---|
| QIB | 177.12x |
| bNII | 0.16x |
| sNII | 0.75x |
| Retail | 1.72x |
| Total | 2.77x |
There was no anchor book. By the close on 28 September, the tiny QIB portion was bid 177.12 times, big HNIs 0.16 times, small HNIs 0.75 times and retail 1.72 times, for 2.77 times overall across 1,984 applications.
What to weigh now
A commodity business
Flour milling margins depend on wheat procurement prices, government stock limits and export policies. Profits can swing with each harvest.
Very short track record
The company was incorporated in 2023 and most of its growth came in a single year. Investors have little history to judge how it handles a bad season.
Strengths and risks
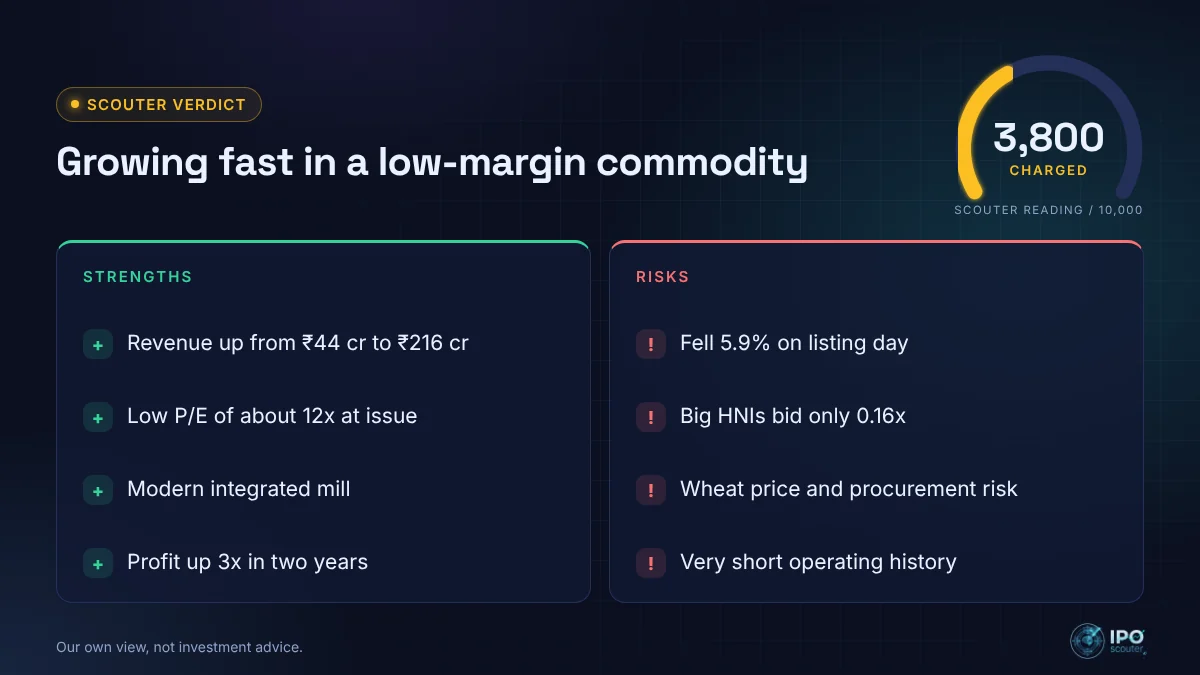
Strengths
- Revenue up nearly five times in two years
- Profit up three times to ₹15.8 crore
- Low post-issue P/E of about 12x at issue
- Modern integrated milling unit
- Entirely fresh issue; no promoter sold shares
Risks
- Fell 5.9% to the lower circuit on listing day
- Weak HNI demand: big HNIs bid only 0.16 times
- Thin margins in a commodity business
- Exposure to wheat prices and government policy
- Incorporated in 2023; very short track record
Scouter verdict: Fast growth and a low P/E, but a thin-margin commodity business with a very short history and weak investor interest. The debut reflected those doubts. This is our own view, not investment advice.
What to watch from here
- Price action on 5 October after the lower-circuit close
- Wheat procurement costs for the new season
- Capacity expansion progress
Peshwa Wheat IPO: frequently asked questions
Peshwa Wheat listed at ₹100.05 on BSE SME on 1 October 2026, against an issue price of ₹101.
The stock closed at ₹95.05, the lower circuit, down 5.9% from the issue price.
It was subscribed 2.77 times overall, with QIB at 177.12x on a tiny quota, NII at about 0.36x and retail at 1.72x.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 1 October 2026 (2 October was a market holiday).
On this page
Key valuation
| Listing loss (close) | -5.9% |
| P/E at issue (post) | 12.2x |
| ROE | 45.0% |
| Net margin | 7.3% |
| Debt to equity | 0.55 |
| Anchor money | Nil |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon