Omara Ventures India IPO: GMP, Subscription Status, Review and Allotment Odds
Chandigarh-based diamond jewellery brand selling necklaces, rings, earrings and bridal pieces through a single boutique, with in-house design and outsourced manufacturing.
A huge one-year jump in profit from a single boutique, with high debt and margins that look unusual for jewellery retail. Retail demand is weak and the GMP is flat.
Our own view, not investment advice.
Subscription by category
Times subscribed, snapshot at 5:06 PM on 1 Oct 2026
Key numbers
FY26, restated
| Revenue | ₹45.87 cr |
| Net profit | ₹9.37 cr |
| Net margin | 20.4% |
| ROE | 74.8% |
| Debt to equity | 1.79 |
| P/E post-issue | 14.5x |
IPO timeline
2 Oct was a market holiday. Monday 5 Oct is the last bidding day.
Omara Ventures India runs a single diamond jewellery boutique in Chandigarh under the Omara brand. In FY26 its revenue nearly doubled to ₹45.9 crore and its profit more than tripled to ₹9.4 crore. It now wants ₹41.99 crore from the BSE SME platform, much of it to repay debt.
On paper the price of about 14.5 times post-issue earnings is reasonable. But this is essentially a one-store business whose profit was ₹31 lakh just two years ago, with a net margin above 20% that is far higher than listed jewellery chains manage. Retail investors have noticed: the retail book was only 16% subscribed after two days.
Omara Ventures India IPO at a glance
| Detail | Omara Ventures India IPO |
|---|---|
| Issue size | ₹41.99 crore (13.50 lakh shares, entirely fresh issue) |
| Price band | ₹296 to ₹311 per share (face value ₹10) |
| Lot size | 400 shares |
| Individual investor minimum | 2 lots, 800 shares (₹2,48,800) |
| sHNI minimum | 3 lots, 1,200 shares (₹3,73,200) |
| Quota (net issue) | Retail 40%, NII 40%, QIB 20% |
| Anchor round | None |
| Bidding dates | 30 Sep to 5 Oct 2026 |
| Allotment | 6 Oct 2026 |
| Refund and demat credit | 7 Oct 2026 |
| Listing | 8 Oct 2026 on BSE SME |
| Market cap at upper band | About ₹135.60 crore post-issue |
| Promoter holding | 99.99% before, 69.03% after |
| Lead manager | Wealth Mine Networks |
| Registrar | Bigshare Services |
| Market maker | Rikhav Securities |
Individuals must apply for at least two lots, or ₹2,48,800 at the upper band. Monday 5 October is the last day to bid.
What Omara Ventures India actually does
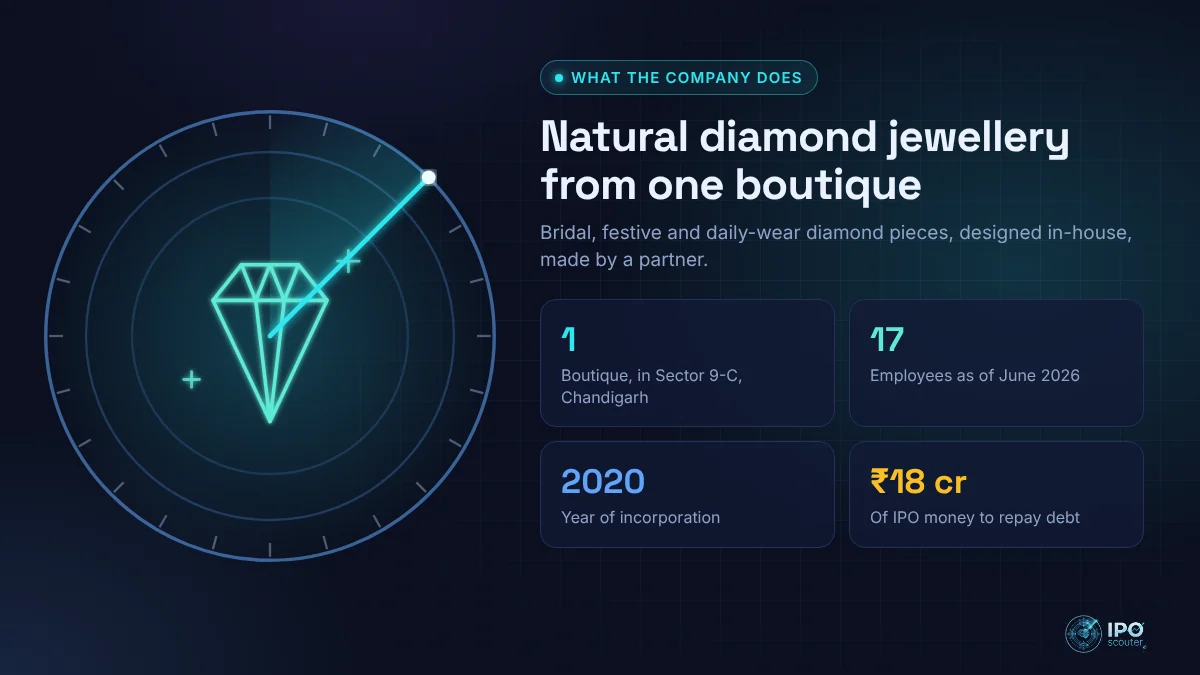
Omara Ventures India Ltd was incorporated in October 2020 and is promoted by Samarth Jaiswal and Ishani Mehta Jaiswal. It sells natural diamond jewellery in gold, platinum and silver, including necklaces, earrings, rings and bracelets for weddings, festivals and daily wear, and offers custom pieces.
Everything is sold through one boutique at SCO 162-163, Sector 9-C, Chandigarh. Designs are created in-house and manufacturing is outsourced to a partner. The company uses BIS hallmarking for gold and GIA grading for diamonds. It had 17 employees as of 30 June 2026.
The IPO money is split mainly between repaying ₹18 crore of debt and ₹10 crore of working capital, with ₹2 crore each for renovating and expanding the boutique and for marketing.
The numbers behind the business
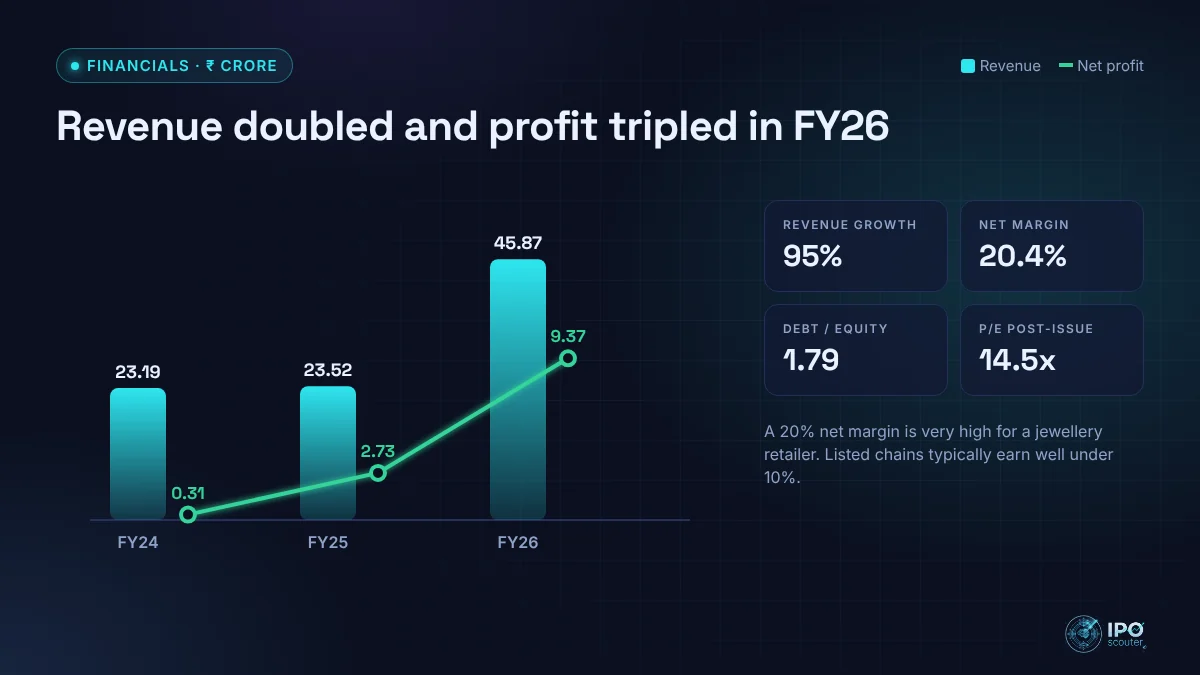
Here are the figures from the offer documents, in ₹ crore, as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Total income | 23.19 | 23.52 | 45.87 |
| EBITDA | 1.84 | 4.87 | 14.43 |
| Net profit | 0.31 | 2.73 | 9.37 |
| Net worth | 0.43 | 3.16 | 12.52 |
| Borrowings | 11.25 | 13.95 | 22.43 |
| Total assets | 26.44 | 29.46 | 47.25 |
What these numbers tell us, in plain language:
- FY26 was a breakout year. Revenue was flat at about ₹23 crore in FY24 and FY25, then jumped 95% to ₹45.9 crore. Profit went from ₹0.31 crore to ₹2.73 crore to ₹9.37 crore.
- The margins need scrutiny. EBITDA margin was 31.5% and net margin 20.4% in FY26. Large listed jewellery retailers typically earn net margins in the single digits because gold is expensive and competition is intense. Higher-margin custom diamond work can explain some of the gap, but investors should ask how repeatable FY26 is.
- Debt is high. Borrowings rose to ₹22.4 crore against net worth of ₹12.5 crore, a debt to equity ratio of 1.79. The ₹18 crore repayment from the IPO would cut this substantially.
- Returns are inflated by a tiny equity base. ROE of 74.8% reflects net worth that was under ₹1 crore two years ago.
How the subscription is playing out, day by day
| Category | Day 2 (1 Oct, 5:06 PM) |
|---|---|
| QIB | 1.00x |
| NII | 1.07x |
| Retail | 0.16x |
| Total | 0.69x |
By 5:06 PM on 1 October the issue was covered 0.69 times overall: QIB at 1.00x, NII at 1.07x and retail at just 0.16x. Retail investors hold 40% of the issue, so the final day needs a big pickup from them.
The GMP story so far
The grey market premium was flat at ₹0 as of 4 October, pointing to a listing near ₹311.
How to check Omara Ventures India IPO allotment status
- Go to the Bigshare Services IPO allotment page, or the BSE allotment status page.
- Select Omara Ventures India from the list of issues.
- Enter your PAN, application number or DP/Client ID.
- Submit to see how many shares you were allotted.
Allotment is expected on 6 Oct 2026, with refunds and demat credit on 7 Oct. Shares are due to list on BSE SME on 8 Oct 2026.
The listing outlook
The grey market expects a flat listing around ₹311. Weak retail demand and the single-store model make a listing gain unlikely unless the final day surprises.
What to weigh before you apply
One boutique carries everything
With a single store, any local disruption, a change in the Chandigarh market or the loss of a few big wedding clients could hit revenue hard. The company plans to expand, but it has not yet proven it can replicate the model.
One exceptional year
Almost all of the earnings that make the valuation look cheap come from FY26. If FY27 looks more like FY25, the P/E on today’s price would be far higher.
Strengths and risks
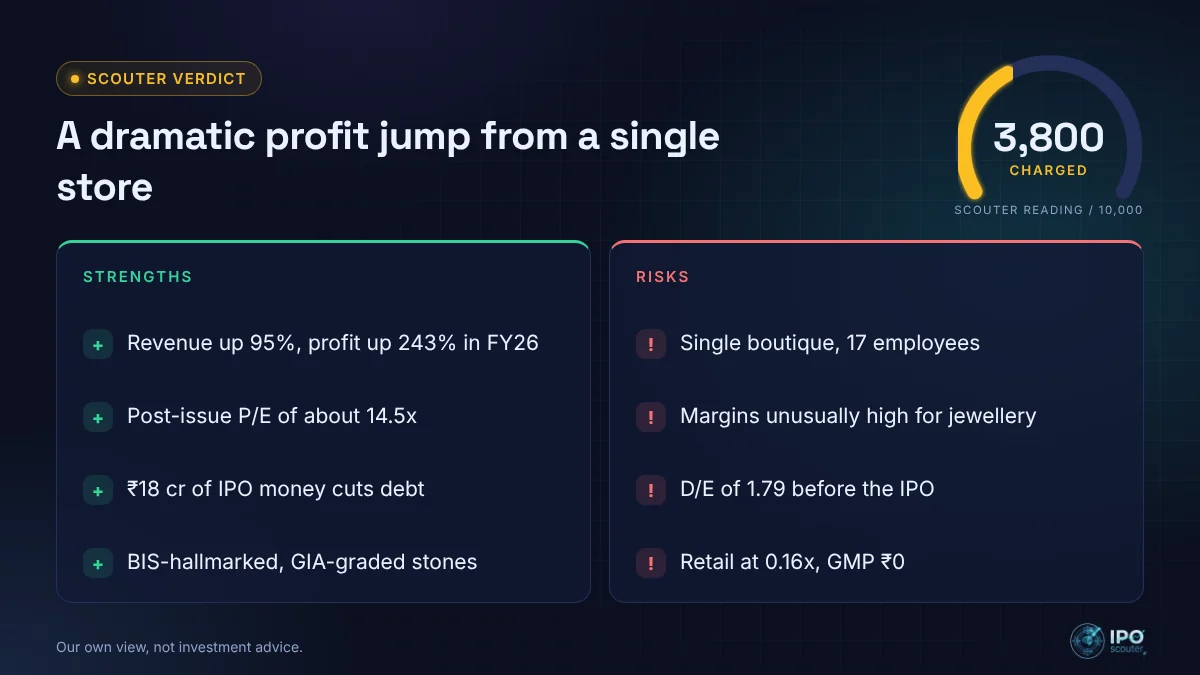
Strengths
- Revenue up 95% and profit up 243% in FY26
- Post-issue P/E of about 14.5x on FY26 earnings
- ₹18 crore of the IPO will repay debt
- BIS hallmarking and GIA-graded diamonds
- Entirely fresh issue; no promoter is selling
Risks
- Single boutique and only 17 employees
- Net margin of 20% is unusually high for jewellery retail
- Debt to equity of 1.79 before the IPO
- Profit was just ₹31 lakh in FY24
- Retail at 0.16x on day 2; GMP at ₹0
- Price to book of about 7.5x
Scouter verdict: A small jewellery boutique with one spectacular year, high debt and margins well above industry norms. Until it shows the FY26 performance can be repeated, we would stay cautious. This is our own view, not investment advice.
Your chances of getting an allotment
- The retail quota works out to about 1,282 lots. Under SEBI’s SME rules every individual investor applies for the minimum of two lots (800 shares, ₹2,48,800), so roughly 641 retail applications can be filled in full.
- Once the retail book is oversubscribed, allotment is decided by a random draw. Every successful applicant gets the minimum application size; nobody gets a partial one.
- Applying for more than the minimum does not improve your retail odds. Separate applications from different PANs in your family do.
What to watch from here
- Retail subscription on 5 October
- Whether the GMP moves off zero
- Allotment status on 6 October through Bigshare Services
- Listing on 8 October
- After listing: whether FY27 margins stay near FY26 levels and progress on new stores
Omara Ventures India IPO: frequently asked questions
The price band is ₹296 to ₹311 per share with a lot size of 400 shares. Individual investors must apply for at least 2 lots (800 shares), which costs ₹2,48,800 at the upper band.
By 5:06 PM on 1 October 2026 the issue was subscribed 0.69 times overall, with QIB at 1.00x, NII at 1.07x and retail at 0.16x. The issue closes on 5 October 2026.
The grey market premium was ₹0 on 4 October 2026, pointing to a listing near the upper band. GMP is unofficial and can change quickly.
It sells natural diamond jewellery under the Omara brand through a single boutique in Chandigarh, with in-house design and outsourced manufacturing.
About ₹18 crore will repay debt, ₹10 crore will fund working capital, and ₹2 crore each will go to boutique expansion and marketing.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 4 October 2026.
On this page
Key valuation
| P/E (pre-issue) | 10.0x |
| P/E (post-issue) | 14.5x |
| P/B | 7.5x |
| ROE | 74.8% |
| Net margin | 20.4% |
| Debt to equity | 1.79 |
| Anchor money | Nil |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon