Liqvd Digital India IPO: Listing Price, Performance and Review
Mumbai-based digital marketing agency offering social media, media buying, content, influencer marketing, SEO and performance marketing, with a US arm through AdLift.
Fast, acquisition-boosted growth at a fair price, but a crowded agency market and weak retail demand led to a lower-circuit debut.
Our own view, not investment advice.
Subscription by category
Final subscription, 25 Sep 2026, 6:52 PM
Listing day, 30 Sep
BSE SME prices
| Issue price | ₹54.00 |
| Open | ₹53.73 |
| High | ₹53.73 |
| Low | ₹51.05 |
| Close | ₹51.05 |
| Loss at close | -5.6% |
IPO timeline
Liqvd Digital India slipped on its debut. The ₹39.01 crore BSE SME issue, priced at ₹54, opened at ₹53.73 on 30 September and fell to the 5% lower circuit, closing at ₹51.05, down 5.6%.
The digital marketing agency had drawn 5.08 times subscription, but that was almost entirely from big HNIs; retail bid only 1.43 times.
How Liqvd Digital India listed
| Detail | Value |
|---|---|
| Issue price | ₹54 |
| Listing price (BSE SME) | ₹53.73 (-0.5%) |
| Day’s high | ₹53.73 |
| Day’s low | ₹51.05 |
| Listing day close | ₹51.05 (-5.5%) |
The stock never traded above its opening price. The next trading session after the 2 October holiday is on Monday 5 October.
Liqvd Digital India IPO at a glance
| Detail | Liqvd Digital India IPO |
|---|---|
| Issue size | ₹39.01 crore (₹34.14 crore fresh + ₹4.87 crore OFS) |
| Issue price | ₹54 per share (face value ₹5) |
| Lot size | 2,000 shares |
| Individual investor minimum | 2 lots, 4,000 shares (₹2,16,000) |
| Anchor round | None reported |
| Bidding dates | 23 Sep to 25 Sep 2026 |
| Allotment | 28 Sep 2026 |
| Listing | 30 Sep 2026 on BSE SME |
| Promoter holding | 78.04% before, 51.83% after |
| Lead manager | Indorient Financial Services |
| Registrar | Bigshare Services |
| Market maker | Shreni Shares |
What Liqvd Digital India actually does
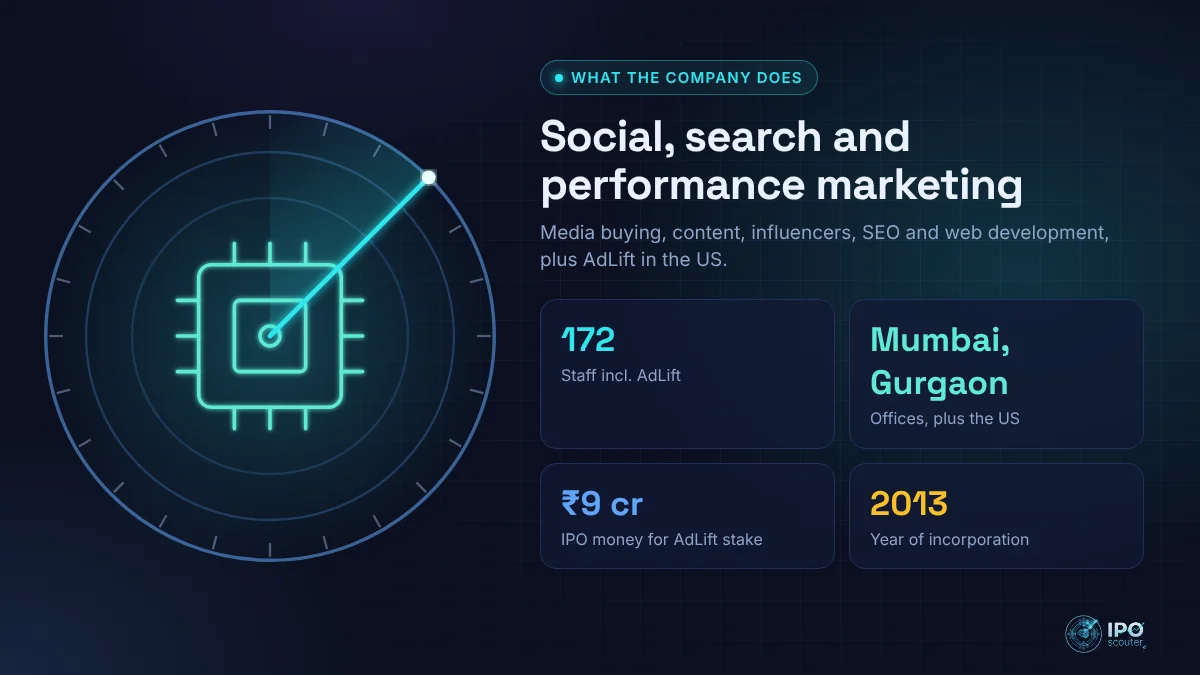
Liqvd Digital India Ltd was incorporated in 2013 and is promoted by Arnab Mitra, Ashish Motilal Jalan, Vivek Suchanti and Concept Communication Ltd. It offers social media management, media planning and buying, content production, influencer marketing, SEO, performance marketing and web and app development.
Clients span IT, FMCG, logistics, financial services, manufacturing and healthcare. It has offices in Mumbai and Gurgaon and a US presence through AdLift Inc., which it is acquiring a larger stake in. The company had 53 employees plus 119 at AdLift.
The IPO funds the AdLift stake (₹9 crore), a video production hub (₹10.59 crore) and working capital (₹6.57 crore). Arnab Mitra sold ₹4.87 crore of shares through the OFS.
The numbers behind the business
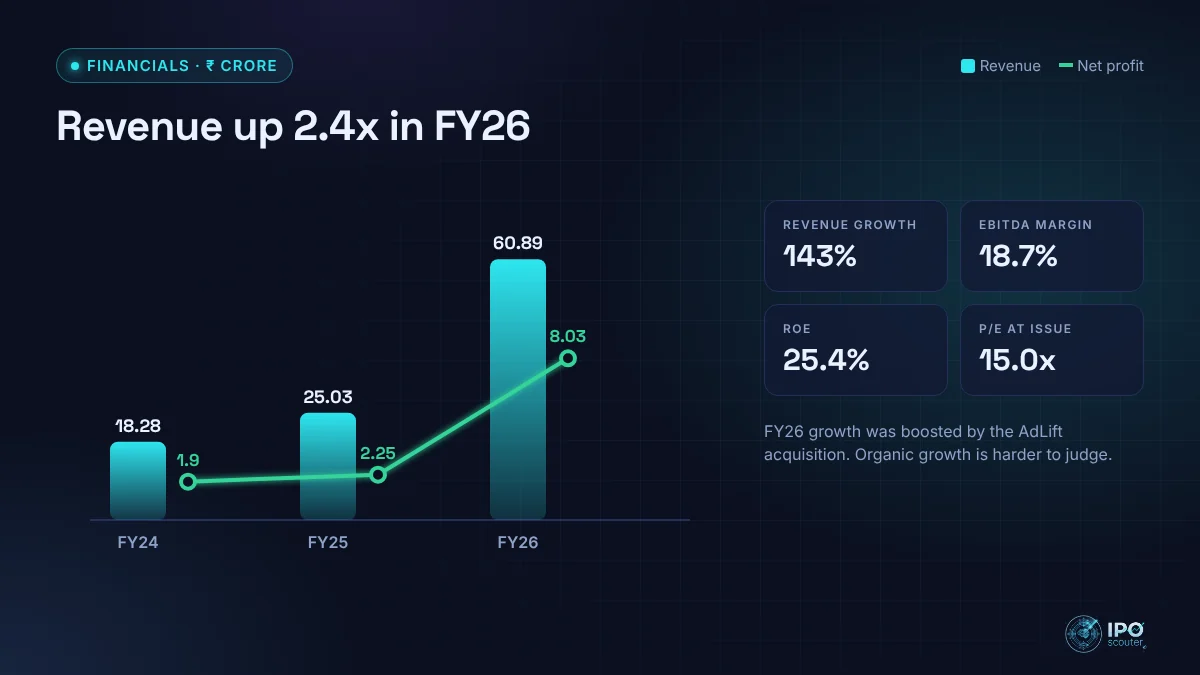
Here are the figures from the offer documents, in ₹ crore, as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 18.28 | 25.03 | 60.89 |
| EBITDA | 3.81 | 3.93 | 11.26 |
| Net profit | 1.9 | 2.25 | 8.03 |
| Net worth | 2.1 | 19.39 | 34.19 |
| Total assets | 13.83 | 33.33 | 57.83 |
What these numbers tell us, in plain language:
- FY26 growth was dramatic. Revenue jumped from ₹25 crore to ₹60.9 crore and profit from ₹2.3 crore to ₹8 crore. Much of that reflects consolidating AdLift.
- Margins improved. EBITDA margin rose to 18.7% and net margin to 13.2%.
- Low debt. Borrowings were ₹9.8 crore, debt to equity 0.29.
- Fair valuation. Post-issue P/E was about 15x at the issue price.
How the subscription ended
| Category | Final (25 Sep) |
|---|---|
| QIB | 1.00x |
| bNII | 27.11x |
| sNII | 2.33x |
| Retail | 1.43x |
| Total | 5.08x |
By the close on 25 September, the QIB portion was exactly covered at 1.00 times, big HNIs bid 27.11 times, small HNIs 2.33 times and retail 1.43 times, for 5.08 times overall across 2,998 applications.
What to weigh now
How much growth is organic?
With AdLift consolidated, FY26 numbers are not directly comparable with earlier years. Investors will want to see organic growth in the next few quarters.
A crowded agency market
Digital marketing has low barriers to entry, and clients can switch agencies easily. Margins depend on retaining key clients and talent.
Strengths and risks
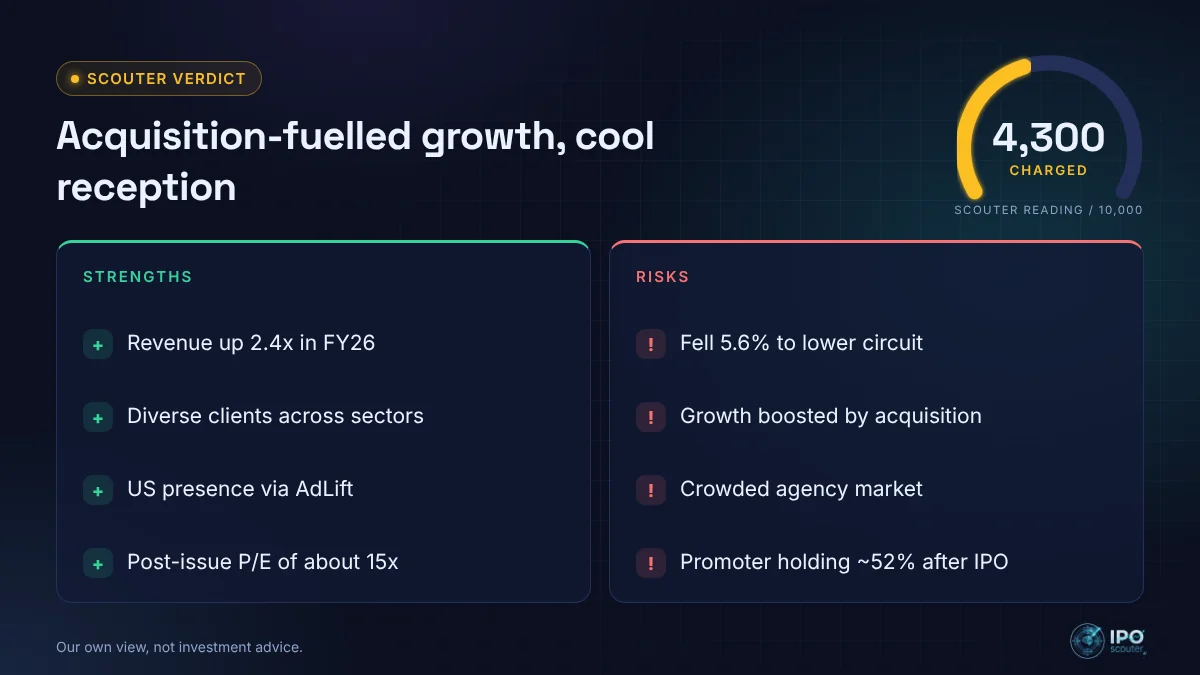
Strengths
- Revenue up 2.4 times and profit up 3.6 times in FY26
- Clients across many sectors
- US presence via AdLift
- Low debt and a post-issue P/E of about 15x
- Investing in a video production hub
Risks
- Fell 5.6% to the lower circuit on listing day
- FY26 growth boosted by an acquisition
- Highly competitive, low-barrier industry
- Promoter holding drops to about 52%
- Promoter sold shares through the OFS
Scouter verdict: A growing agency with a reasonable price, but the acquisition-driven numbers and a crowded market made investors cautious, as the debut showed. This is our own view, not investment advice.
What to watch from here
- Price action on 5 October after the lower-circuit close
- Organic revenue growth excluding AdLift
- Client wins and retention
Liqvd Digital India IPO: frequently asked questions
Liqvd Digital India listed at ₹53.73 on BSE SME on 30 September 2026, against an issue price of ₹54.
The stock closed at ₹51.05, the lower circuit, down 5.6% from the issue price.
It was subscribed 5.08 times overall, with QIB at 1.00x, NII at 21.02x and retail at 1.43x.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 1 October 2026 (2 October was a market holiday).
On this page
Key valuation
| Listing loss (close) | -5.6% |
| P/E at issue (post) | 15.0x |
| ROE | 25.4% |
| EBITDA margin | 18.7% |
| Debt to equity | 0.29 |
| Anchor money | Nil |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon