Himalayan Solar IPO: Allotment Status, GMP, Listing Date and Review
Panchkula-based maker of solar water pumping systems, PV modules and inverters, with 100 MW of module capacity and over 85,000 HP of solar pumps installed.
Cheap on earnings at about 11 times, with fast profit growth. But demand was weak, the GMP is flat, and solar pump demand leans heavily on government schemes.
Our own view, not investment advice.
Subscription by category
Final subscription, 29 Sep 2026, 6:55 PM
Key numbers
FY26, proforma consolidated
| Revenue | ₹171.69 cr |
| Net profit | ₹20.67 cr |
| EBITDA margin | 17.1% |
| Module capacity | 100 MW |
| Debt to equity | 0.77 |
| Anchor money | ₹7.75 cr |
IPO timeline
Allotment was finalised on 30 Sep and refunds and demat credits went out on 1 Oct. Shares list on Monday 5 Oct.
Himalayan Solar makes solar water pumps for farms, along with solar panels, inverters and rooftop systems. Its ₹68.03 crore NSE SME issue was priced at just 11 times post-issue earnings, yet investors stayed lukewarm: the issue was only 1.19 times subscribed.
Allotment is done and shares list on 5 October. With the grey market premium flat at zero, a listing near the ₹103 issue price looks likely.
Himalayan Solar IPO at a glance
| Detail | Himalayan Solar IPO |
|---|---|
| Issue size | ₹68.03 crore (₹60.68 crore fresh + ₹7.35 crore OFS) |
| Issue price | ₹103 per share (face value ₹10) |
| Lot size | 1,200 shares |
| Individual investor minimum | 2 lots, 2,400 shares (₹2,47,200) |
| Quota | Retail 50.04%, NII 29.95%, QIB 20.01% |
| Anchor round | ₹7.75 crore on 24 Sep 2026 |
| Bidding dates | 25 Sep to 29 Sep 2026 |
| Allotment | 30 Sep 2026 |
| Refund and demat credit | 1 Oct 2026 |
| Listing | 5 Oct 2026 on NSE SME (symbol HIMALAYAN) |
| Market cap | About ₹227.73 crore post-issue |
| Promoter holding | 100% before, 70.13% after |
| Lead manager | Finshore Management Services |
| Registrar | Maashitla Securities |
| Market maker | Anant Securities |
Retail was subscribed only 1.26 times across 1,652 applications, so most retail applicants should have received the minimum two lots (2,400 shares).
What Himalayan Solar actually does
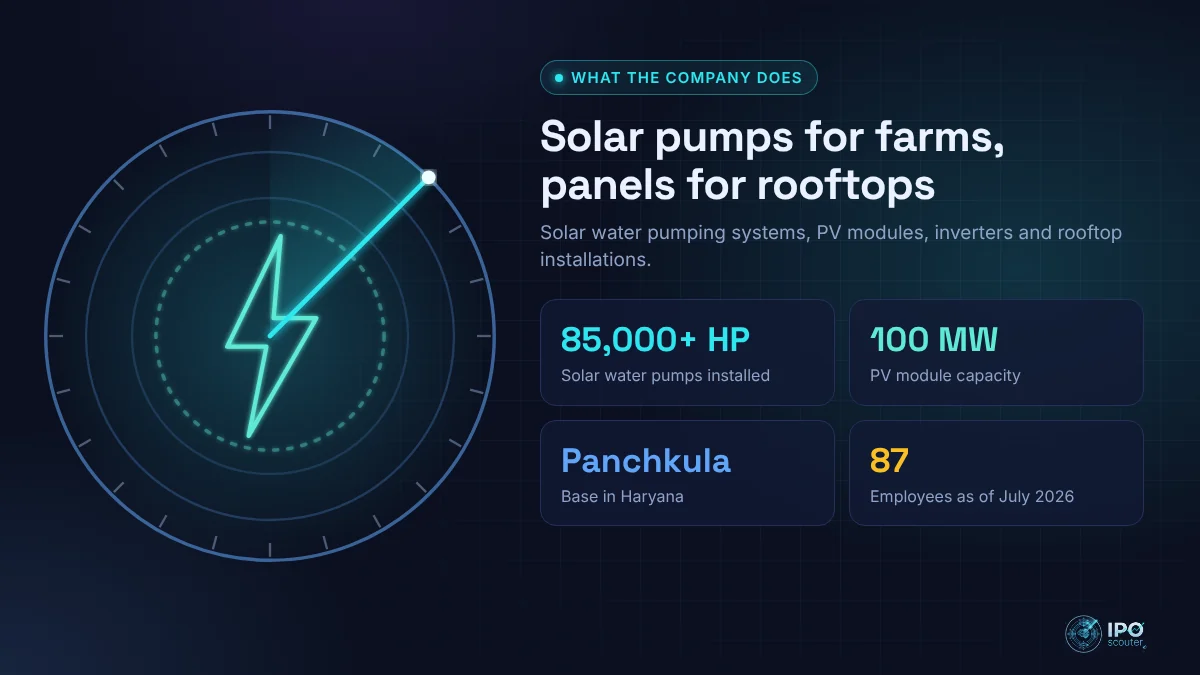
Himalayan Solar Ltd was incorporated in 2015 and is promoted by Manjeet Singh, Karthiyani M, Himanshu Dalal, Mehtab Singh and Anita Kumari. Based in Panchkula, Haryana, it designs, manufactures, supplies and installs solar water pumping systems, solar PV modules (polycrystalline and Mono PERC), solar inverters and rooftop systems.
It has 40 MW of polycrystalline and 60 MW of Mono PERC module capacity and says it has installed more than 85,000 HP of solar water pumping systems. Solar pumps in India are largely sold through government subsidy programmes for farmers, which drive much of the sector’s demand. The company had 87 employees in July 2026.
IPO money will fund working capital (₹29.5 crore), new machinery (₹12.98 crore), debt repayment (₹2.12 crore) and general purposes. Karthiyani M is selling ₹7.35 crore of shares through the OFS.
The numbers behind the business
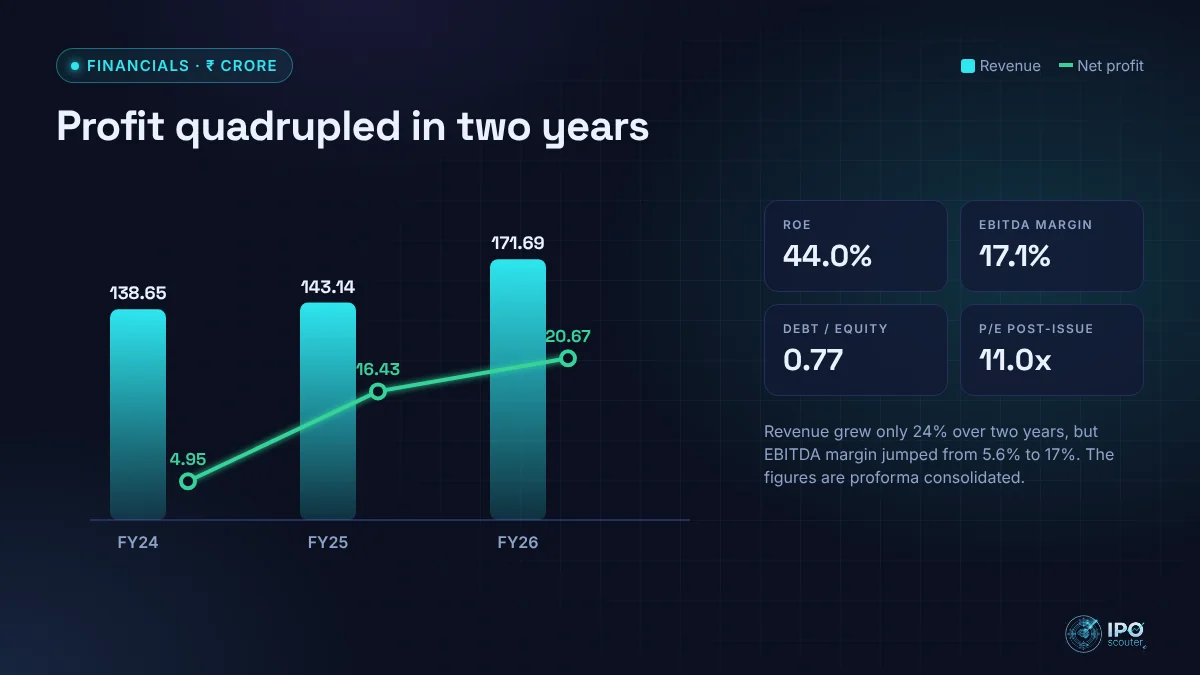
Here are the figures from the offer documents, in ₹ crore, on a proforma consolidated basis as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 138.65 | 143.14 | 171.69 |
| EBITDA | 7.83 | 23.58 | 29.04 |
| Net profit | 4.95 | 16.43 | 20.67 |
| Net worth | 10.33 | 26.46 | 46.93 |
| Borrowings | 23.54 | 26.95 | 36.12 |
| Total assets | 84.14 | 93.82 | 158.22 |
What these numbers tell us, in plain language:
- Margins transformed the business. Revenue grew modestly from ₹138.7 crore to ₹171.7 crore over two years, but EBITDA jumped from ₹7.8 crore to ₹29 crore and profit from ₹5 crore to ₹20.7 crore.
- The figures are proforma consolidated. That means they show the group as if its current structure had existed throughout the period, which can flatter comparisons. Investors should read the RHP notes before relying on the trend.
- Debt is moderate. Borrowings were ₹36.1 crore in FY26, with debt to equity of 0.77. Total assets jumped 69% in FY26, likely reflecting inventory and receivables.
- The valuation is undemanding. Post-issue P/E is about 11x, well below most solar peers.
How the subscription ended
| Category | Final (29 Sep) |
|---|---|
| QIB | 1.66x |
| bNII | 1.27x |
| sNII | 0.29x |
| Retail | 1.26x |
| Total | 1.19x |
Anchors put in ₹7.75 crore on 24 September. By the close on 29 September, QIBs had bid 1.66 times, big HNIs 1.27 times, small HNIs 0.29 times and retail 1.26 times, for 1.19 times overall. For an SME solar issue at this price, that is a weak response.
The GMP story so far
The grey market premium was flat at ₹0 as of 4 October, pointing to a listing near the ₹103 issue price.
How to check Himalayan Solar IPO allotment status
- Go to the Maashitla Securities IPO allotment page, or the NSE allotment status page.
- Select Himalayan Solar from the list of issues.
- Enter your PAN, application number or DP/Client ID.
- Submit to see how many shares you were allotted.
The basis of allotment was finalised on 30 September 2026. Refunds for unsuccessful applicants and share credits to demat accounts were processed on 1 October. If shares were allotted, they should already show in your demat account and will be tradable from the listing on 5 October on NSE SME.
The listing outlook
A flat listing around ₹103 looks likely. If the stock holds that level, its low valuation could attract buyers over time, but the near-term catalyst is weak.
What to weigh before you apply
Dependence on government schemes
Demand for solar pumps rises and falls with central and state subsidy budgets and the pace of tenders and payments. Delays in subsidy disbursal can tie up working capital.
A recent margin jump
Most of the profit growth came in FY25, when EBITDA margin tripled. Investors need to see that margin hold through FY27 before trusting the low P/E.
Strengths and risks
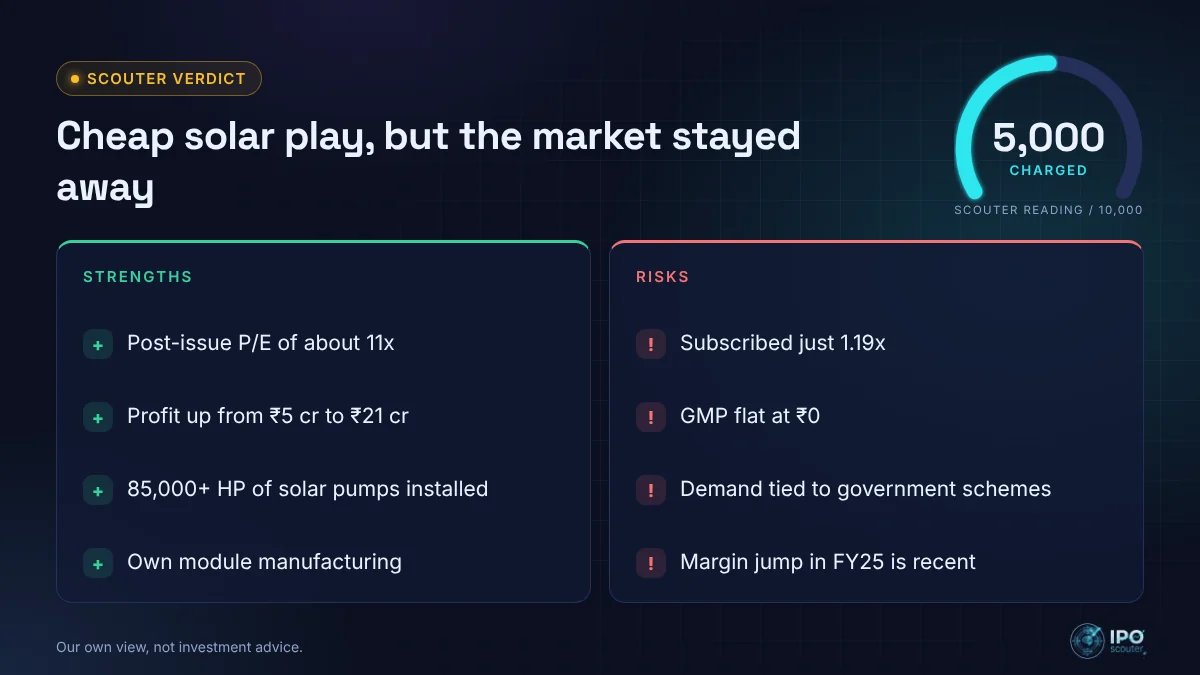
Strengths
- Post-issue P/E of about 11x
- Profit up from ₹4.95 crore to ₹20.67 crore in two years
- Over 85,000 HP of solar pumps installed
- In-house PV module manufacturing
- Anchor book of ₹7.75 crore
Risks
- Subscribed only 1.19 times; GMP flat
- Demand closely tied to government subsidy schemes
- Margin jump is recent; figures are proforma consolidated
- Working capital and receivables risk
- Promoter selling ₹7.35 crore through the OFS
Scouter verdict: Attractively priced on paper, with strong recent profit growth. But the market’s lukewarm response, the policy-driven demand and the recent margin jump keep us neutral. Allottees should expect a flat start. This is our own view, not investment advice.
Your chances of getting an allotment
- Retail investors bid 1.26 times their quota, so most retail applicants should have received the SME minimum of two lots.
- Small HNIs bid only 0.29 times, so all valid sNII applications should have been allotted in full.
What to watch from here
- Listing price on 5 October against ₹103
- Order flow from government solar pump schemes
- Whether EBITDA margin holds near 17%
- Receivables and working capital in the first post-listing results
Himalayan Solar IPO: frequently asked questions
Allotment was finalised on 30 September 2026. You can check it on the Maashitla Securities website or the NSE allotment page using your PAN or application number.
Shares list on NSE SME on Monday, 5 October 2026, under the symbol HIMALAYAN.
The grey market premium was ₹0 on 4 October 2026, pointing to a listing near the ₹103 issue price. GMP is unofficial and can change quickly.
It was subscribed 1.19 times overall, with QIB at 1.66x, NII at 0.94x and retail at 1.26x.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 4 October 2026.
On this page
Key valuation
| P/E (pre-issue) | 8.1x |
| P/E (post-issue) | 11.0x |
| P/B | 3.6x |
| ROE | 44.0% |
| EBITDA margin | 17.1% |
| Debt to equity | 0.77 |
| Anchor money | ₹7.75 cr |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon