ArMee Infotech IPO: Listing Price, Performance and Review
Ahmedabad-based IT infrastructure and managed services provider for government, PSU and corporate clients, with retail ‘Experience Zones’ and a growing solar EPC and battery storage business.
A weak debut confirmed what the subscription hinted: a thin-margin IT reseller with a falling profit trend was priced too richly.
Our own view, not investment advice.
Subscription by category
Final subscription, 25 Sep 2026, 6:54 PM
Listing day, 30 Sep
BSE prices
| Issue price | ₹375.00 |
| Open | ₹368.85 |
| High | ₹372.00 |
| Low | ₹295.10 |
| Close | ₹295.35 |
| 1 Oct close | ₹273.35 |
IPO timeline
ArMee Infotech had one of the worst debuts of the month. Its ₹300 crore IPO, priced at ₹375, opened slightly lower at ₹368.85 on BSE on 30 September and then sold off steadily to close at ₹295.35, down 21.2%. It fell further to ₹273.35 on 1 October, 27% below the issue price.
The warning signs were there: the issue was only 2.62 times subscribed despite a large retail quota, and the valuation was high for a business earning about 3 paise of profit on every rupee of sales.
How ArMee Infotech listed
| Detail | Value |
|---|---|
| Issue price | ₹375 |
| Listing price (BSE) | ₹368.85 (-1.6%) |
| Day’s high | ₹372.00 |
| Day’s low | ₹295.10 |
| Listing day close | ₹295.35 (-21.2%) |
| NSE close | ₹300.00 (-20.0%) |
| Price on 1 Oct | ₹273.35 (-27.1%) |
For a retail investor with one lot of 40 shares, the ₹15,000 investment was worth ₹11,814 at the BSE close of ₹295.35, a loss of about ₹3,190 on day one. By 1 October, at ₹273.35, the loss on one lot had grown to about ₹4,070, or 27%.
The stock hit its day’s low almost at the close, suggesting sustained selling rather than a brief dip. The next trading session after the 2 October holiday is on Monday 5 October.
ArMee Infotech IPO at a glance
| Detail | ArMee Infotech IPO |
|---|---|
| Issue size | ₹300 crore (entirely fresh issue) |
| Issue price | ₹375 per share (face value ₹10) |
| Lot size | 40 shares (₹15,000) |
| Quota | Retail 52.5%, QIB 25%, NII 22.5% |
| Anchor round | ₹39.94 crore on 22 Sep 2026 |
| Bidding dates | 23 Sep to 25 Sep 2026 |
| Allotment | 28 Sep 2026 |
| Listing | 30 Sep 2026 on BSE and NSE |
| Promoter holding | 92.72% before, 69.35% after |
| Lead managers | Khandwala Securities, Saffron Capital Advisors |
| Registrar | Cameo Corporate Services |
What ArMee Infotech actually does
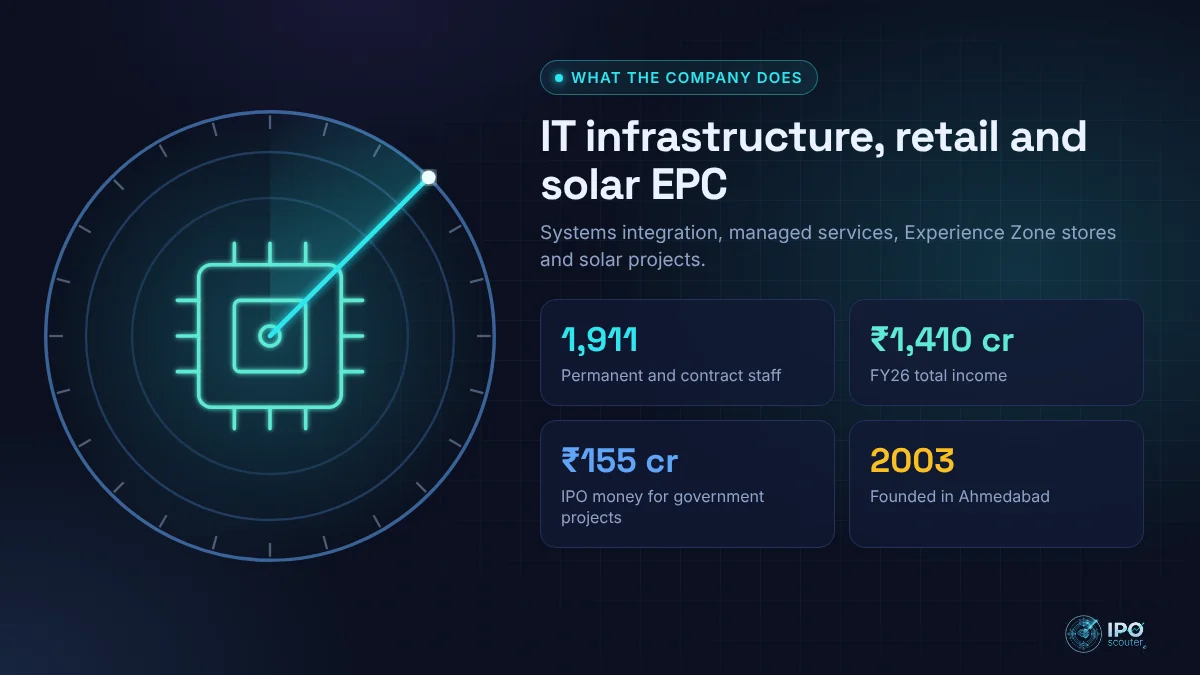
ArMee Infotech Ltd was founded in 2003 in Ahmedabad and is promoted by Ami Ridhish Patel, Kiritkumar Chimanbhai Patel and Ridhish Kiritbhai Patel. It provides IT infrastructure solutions and managed services to government, PSU, corporate, banking and education clients, runs retail ‘Experience Zones’, and has a renewable energy arm doing solar EPC, power purchase agreements and battery storage (BESS) projects.
It had 263 permanent and 1,648 contract staff in June 2026. The IPO money was earmarked for government projects (₹155 crore), working capital (₹60 crore) and general purposes.
The numbers behind the business
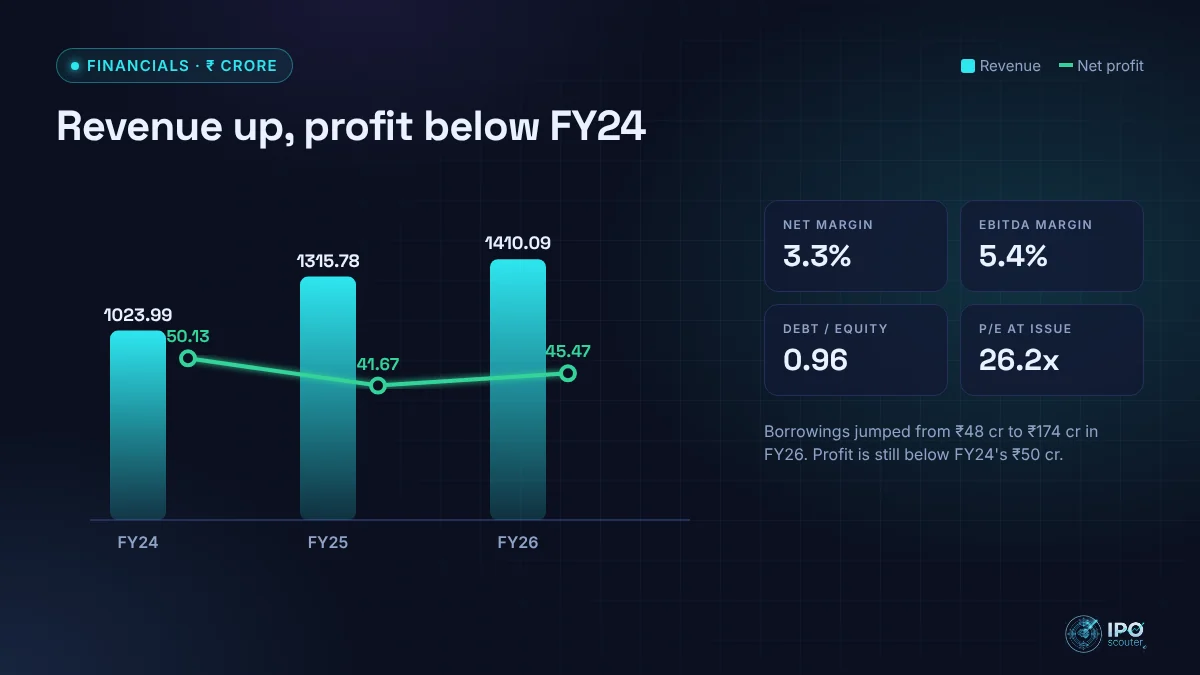
Here are the figures from the offer documents, in ₹ crore, as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Total income | 1,023.99 | 1,315.78 | 1,410.09 |
| EBITDA | 71.58 | 58.64 | 75.64 |
| Net profit | 50.13 | 41.67 | 45.47 |
| Net worth | 95.18 | 136.67 | 182.18 |
| Borrowings | 27.26 | 48.1 | 174.36 |
| Total assets | 673.5 | 828.54 | 958.87 |
What these numbers tell us, in plain language:
- Revenue grows, profit does not. Total income rose from ₹1,024 crore in FY24 to ₹1,410 crore in FY26, but profit fell from ₹50.1 crore to ₹41.7 crore before recovering to ₹45.5 crore.
- Margins are thin. EBITDA margin was 5.4% and net margin 3.3% in FY26, typical of IT hardware reselling and integration.
- Debt jumped. Borrowings rose from ₹48 crore to ₹174 crore in FY26, debt to equity 0.96.
- The valuation was demanding. At ₹375 the post-issue P/E was about 26x, a premium multiple for a low-margin business. The listing-day fall brought it closer to 20x.
How the subscription ended
| Category | Final (25 Sep) |
|---|---|
| QIB | 3.20x |
| bNII | 1.49x |
| sNII | 3.74x |
| Retail | 2.65x |
| Total | 2.62x |
Anchors put in ₹39.94 crore on 22 September. By the close on 25 September, QIBs had bid 3.20 times, big HNIs 1.49 times, small HNIs 3.74 times and retail 2.65 times, for 2.62 times overall across 2.50 lakh applications. That was weak demand for a ₹300 crore mainboard issue.
The GMP story
The grey market saw trouble coming before the listing did. Trackers reported a GMP of about ₹20 when bidding opened on 23 September, but it faded steadily and stood at only about ₹6, or 1.6%, just before listing.
A falling GMP alongside an unexciting subscription is a warning sign, and it proved right on the open, which came in slightly below the issue price. What even a ₹6 GMP did not show was the scale of selling later in the day, which took the stock more than 20% lower. Subscription data also differs between sources for this issue, so we have used the final figures published after closing.
What to weigh now
Is it cheap now?
At around ₹273, the stock trades at roughly 19 times FY26 earnings on the post-issue share count. That is less demanding than the issue price, but still not cheap for a business with 3% net margins and rising debt.
Execution on government projects
Over half the IPO money is meant for government projects. Those can be lumpy and slow to pay, which explains the jump in borrowings.
A large retail quota that retail did not fill with conviction
More than half the issue, 52.5%, was reserved for retail investors. Retail bid 2.65 times, so roughly one applicant in three received a lot. With such a large retail book, that still left a very large number of small holders sitting on the stock at listing. When the price started to slip, many of them sold together. A big retail allotment can make a weak debut worse, because there are fewer long-term holders to absorb the selling.
Strengths and risks
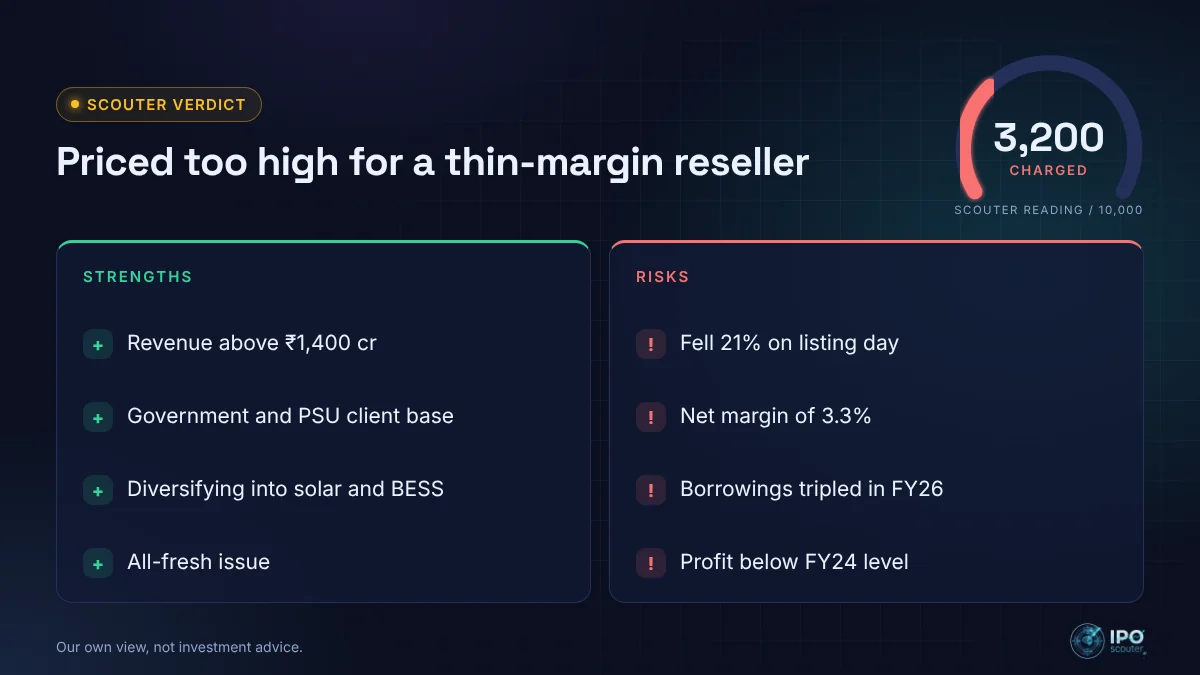
Strengths
- Revenue above ₹1,400 crore
- Long-standing government and PSU client relationships
- Diversification into solar EPC and battery storage
- Entirely fresh issue; no promoter sold shares
Risks
- Fell 21% on listing day and 27% by 1 October
- Net margin of about 3.3%
- Borrowings more than tripled in FY26
- Profit still below FY24 level
- Weak 2.62 times subscription signalled limited demand
Scouter verdict: The market judged this one quickly. A large but thin-margin IT reseller with stagnant profits was priced too high, and the debut reflected that. We see no strong case to buy the dip without evidence of margin improvement. This is our own view, not investment advice.
What to watch from here
- Trading on 5 October after the holiday
- September quarter margins and borrowings
- Order wins in government IT and solar EPC
- Anchor lock-in expiry on 28 October (30 days)
- The anchor lock-in: 50% of the ₹39.94 crore anchor shares can be sold 30 days after allotment, around 28 October, and the rest after 90 days
ArMee Infotech IPO: frequently asked questions
ArMee Infotech listed at ₹368.85 on BSE and ₹375 on NSE on 30 September 2026, against an issue price of ₹375.
The stock closed at ₹295.35 on BSE, down 21.2%, and ₹300 on NSE, down 20%. On 1 October it closed at ₹273.35, down about 27% from the issue price.
It was subscribed 2.62 times overall, with QIB at 3.20x, NII at about 2.24x and retail at 2.65x.
Demand during the IPO was weak, and the issue was priced at about 26 times earnings for a business with net margins of around 3% and rising debt.
The GMP fell from about ₹20 when bidding opened to about ₹6 before listing, a sign of fading demand. GMP is unofficial.
Cameo Corporate Services is the registrar. Check on its website, BSE or NSE using your PAN or application number. Allotment was finalised on 28 September 2026.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 1 October 2026 (2 October was a market holiday).
On this page
Key valuation
| Listing loss (close) | -21.2% |
| P/E at issue (post) | 26.2x |
| Net margin | 3.3% |
| EBITDA margin | 5.4% |
| Debt to equity | 0.96 |
| Anchor money | ₹39.94 cr |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon