Pooja Logistics IPO: Listing Price, Performance and Review
Refrigerated trucking company with 424 GPS-enabled reefer vehicles moving confectionery, dairy, QSR, pharma and e-commerce goods across India.
A steady debut for a growing cold-chain fleet operator at a fair price. Capital-heavy expansion and fuel costs are the risks.
Our own view, not investment advice.
Subscription by category
Final subscription, 25 Sep 2026, 6:55 PM
Listing day, 30 Sep
NSE SME prices
| Issue price | ₹115.00 |
| Open | ₹118.00 |
| High | ₹123.90 |
| Low | ₹118.00 |
| Close | ₹123.90 |
| Gain at close | +7.7% |
IPO timeline
Pooja Logistics had a quiet but positive debut. The ₹44.23 crore NSE SME issue, priced at ₹115, opened at ₹118 on 30 September and climbed to the 5% upper circuit, closing at ₹123.90, up 7.7%.
The refrigerated trucking company drew 3.11 times subscription and ₹12.21 crore from anchor investors.
How Pooja Logistics listed
| Detail | Value |
|---|---|
| Issue price | ₹115 |
| Listing price (NSE SME) | ₹118.00 (+2.6%) |
| Day’s high | ₹123.90 |
| Day’s low | ₹118.00 |
| Listing day close | ₹123.90 (+7.7%) |
Closing at the upper circuit means buyers outnumbered sellers at the end of the day. The next trading session after the 2 October holiday is on Monday 5 October.
Pooja Logistics IPO at a glance
| Detail | Pooja Logistics IPO |
|---|---|
| Issue size | ₹44.23 crore (38.46 lakh shares, entirely fresh issue) |
| Issue price | ₹115 per share (face value ₹10) |
| Lot size | 1,200 shares |
| Individual investor minimum | 2 lots, 2,400 shares (₹2,76,000) |
| Anchor round | ₹12.21 crore on 22 Sep 2026 |
| Bidding dates | 23 Sep to 25 Sep 2026 |
| Allotment | 28 Sep 2026 |
| Listing | 30 Sep 2026 on NSE SME |
| Promoter holding | 93.68% before, 68.45% after |
| Lead manager | Share India Capital Services |
| Registrar | Maashitla Securities |
| Market makers | Prabhat Financial Services, Share India Securities |
What Pooja Logistics actually does
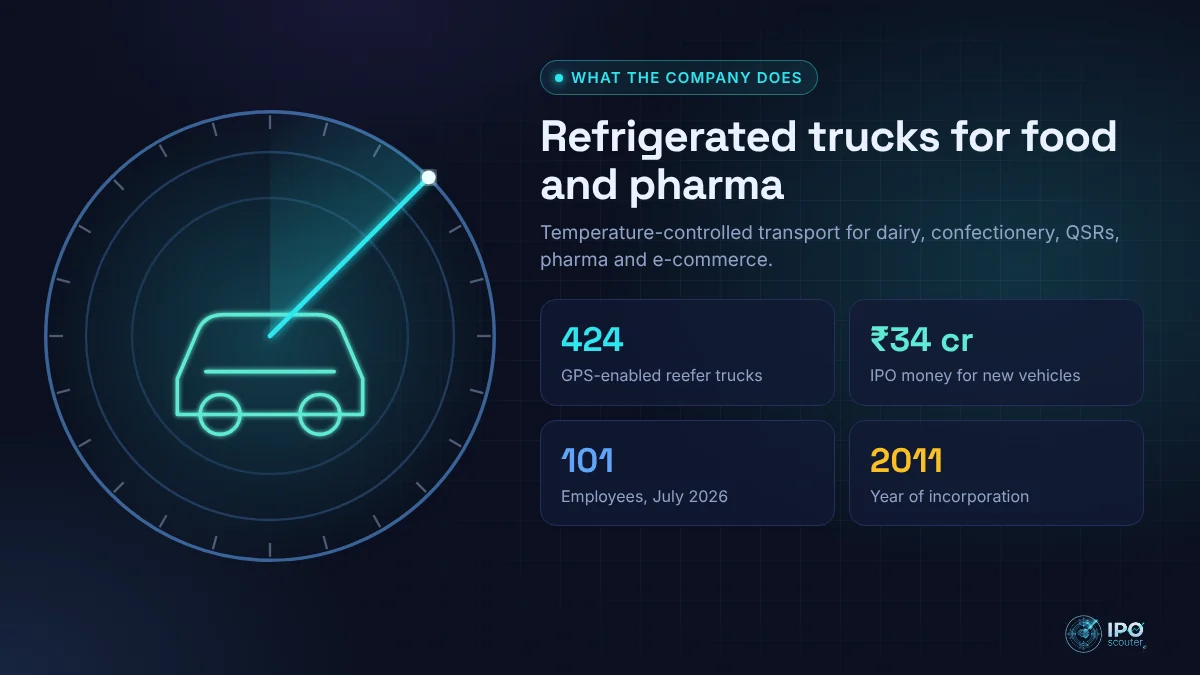
Pooja Logistics Ltd was incorporated in 2011 and is promoted by Deepak Khanna and Anu Khanna. It provides temperature-controlled logistics with a fleet of 424 GPS-enabled refrigerated trucks, or reefers, as of March 2026.
It moves perishable goods for confectionery, dairy, quick-service restaurant, pharmaceutical, e-commerce and retail clients. The company had about 101 employees in July 2026.
Most of the IPO money, ₹33.97 crore, goes to buying more vehicles.
The numbers behind the business
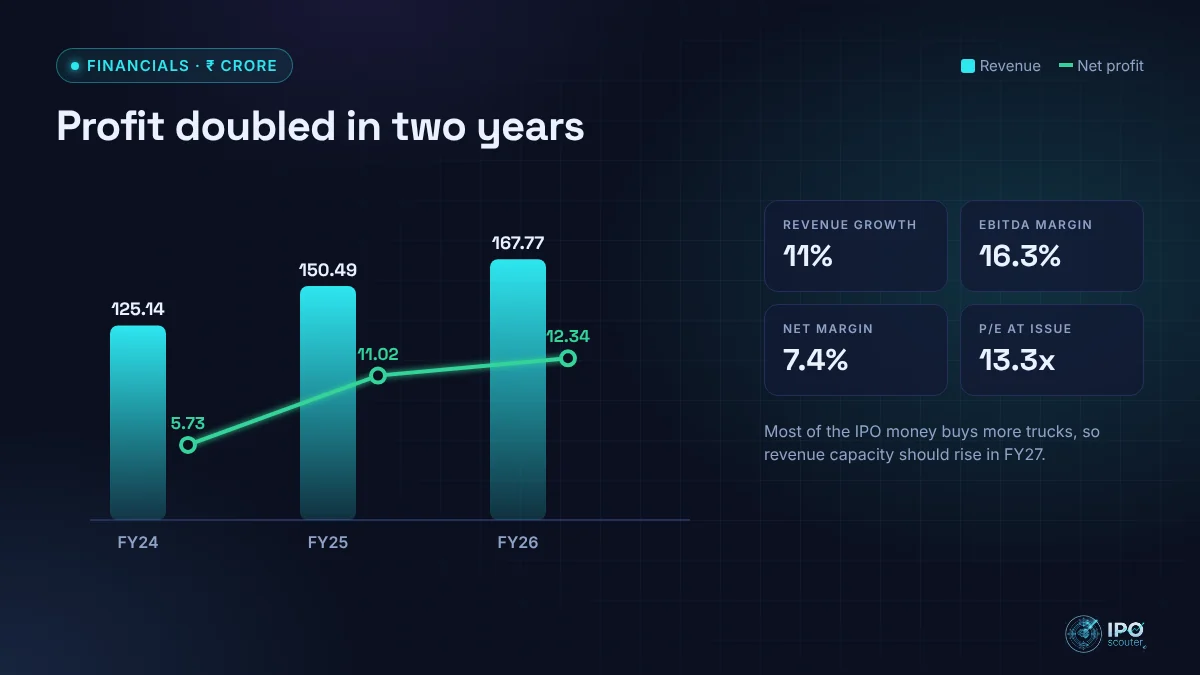
Here are the figures from the offer documents, in ₹ crore, as reported by IPO data sites.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 125.14 | 150.49 | 167.77 |
| EBITDA | 19.13 | 23.09 | 27.3 |
| Net profit | 5.73 | 11.02 | 12.34 |
| Net worth | 14.83 | 25.85 | 42.31 |
| Borrowings | 31.03 | 29 | 39.21 |
| Total assets | 59.78 | 70.06 | 98.13 |
What these numbers tell us, in plain language:
- Steady growth. Revenue rose from ₹125 crore in FY24 to ₹168 crore in FY26, and profit roughly doubled from ₹5.7 crore to ₹12.3 crore.
- Healthy margins for trucking. EBITDA margin was 16.3% and net margin 7.4% in FY26.
- Debt is moderate. Borrowings rose to ₹39.2 crore in FY26 as the fleet grew.
- Fair valuation. Post-issue P/E was about 13.3x at the issue price.
How the subscription ended
| Category | Final (25 Sep) |
|---|---|
| QIB | 2.50x |
| bNII | 5.13x |
| sNII | 4.36x |
| Retail | 2.86x |
| Total | 3.11x |
Anchors put in ₹12.21 crore on 22 September. By the close on 25 September, QIBs had bid 2.50 times, big HNIs 5.13 times, small HNIs 4.36 times and retail 2.86 times, for 3.11 times overall across 1,937 applications.
What to weigh now
A capital-heavy model
Growth in trucking means buying more trucks, which needs capital and adds depreciation and interest. Utilisation rates decide whether new trucks earn their keep.
Fuel and driver costs
Diesel prices and driver availability directly affect margins in road transport. Contracts with large clients may not fully pass on cost increases.
Strengths and risks
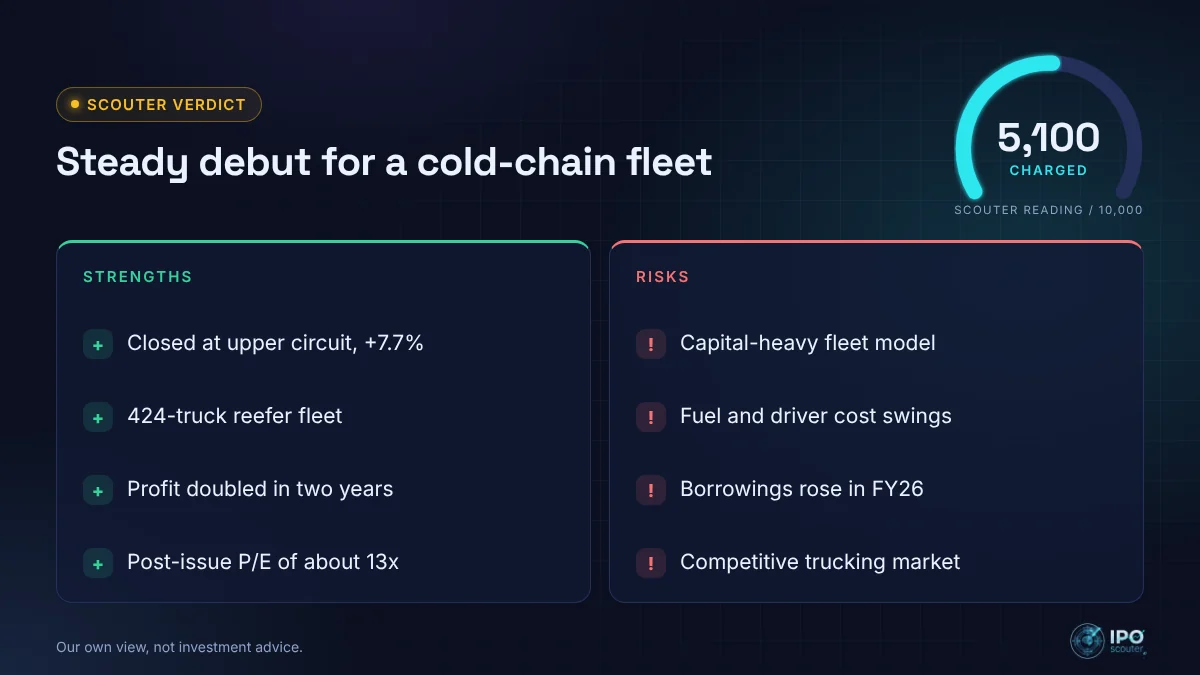
Strengths
- Closed at the upper circuit, up 7.7%
- Fleet of 424 GPS-enabled reefer trucks
- Profit doubled in two years
- Post-issue P/E of about 13x
- Diversified clients across food, pharma and e-commerce
Risks
- Capital-intensive fleet expansion
- Exposure to fuel and driver costs
- Borrowings rose in FY26
- Competitive trucking market
- Thin SME liquidity
Scouter verdict: A growing cold-chain player in a sector with long-term tailwinds, offered at a fair price and rewarded with a steady debut. Execution on fleet expansion is the key watch point. This is our own view, not investment advice.
What to watch from here
- Trading on 5 October
- Fleet additions and utilisation
- Fuel cost trends and margins
- Anchor lock-in expiry on 28 October (30 days)
Pooja Logistics IPO: frequently asked questions
Pooja Logistics listed at ₹118 on NSE SME on 30 September 2026, against an issue price of ₹115.
The stock closed at ₹123.90, the upper circuit, up 7.7% from the issue price.
It was subscribed 3.11 times overall, with QIB at 2.50x, NII at about 4.9x and retail at 2.86x.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 1 October 2026 (2 October was a market holiday).
On this page
Key valuation
| Listing gain (close) | +7.7% |
| P/E at issue (post) | 13.3x |
| EBITDA margin | 16.3% |
| Net margin | 7.4% |
| Fleet | 424 reefers |
| Anchor money | ₹12.21 cr |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Telegram channel launching soon