Paras Healthcare IPO: Subscription Status, GMP Today and Review
Gurugram-based hospital chain running eight hospitals with 2,211 beds across Haryana, Bihar, Uttar Pradesh, Rajasthan, Jharkhand and Jammu and Kashmir, focused on tier 2 and tier 3 cities.
A fast-growing regional hospital chain that has just turned profitable, with rising occupancy, but with heavy debt and a price of about 160 times FY26 earnings.
Our own view, not investment advice.
Key numbers
FY26, restated consolidated
| Revenue | ₹1,605.95 cr |
| EBITDA | ₹335.58 cr |
| Net profit | ₹43.83 cr |
| Bed occupancy | 61.75% |
| ARPOB (per day) | ₹47,398 |
| Debt to equity | 3.53x |
IPO timeline
Bidding is open from 21 to 23 October 2026, alongside Jio Platforms. By the end of day 2 the issue was 0.34 times subscribed, with the retail portion fully covered at 1.31x. Listing on BSE and NSE is scheduled for 28 October.
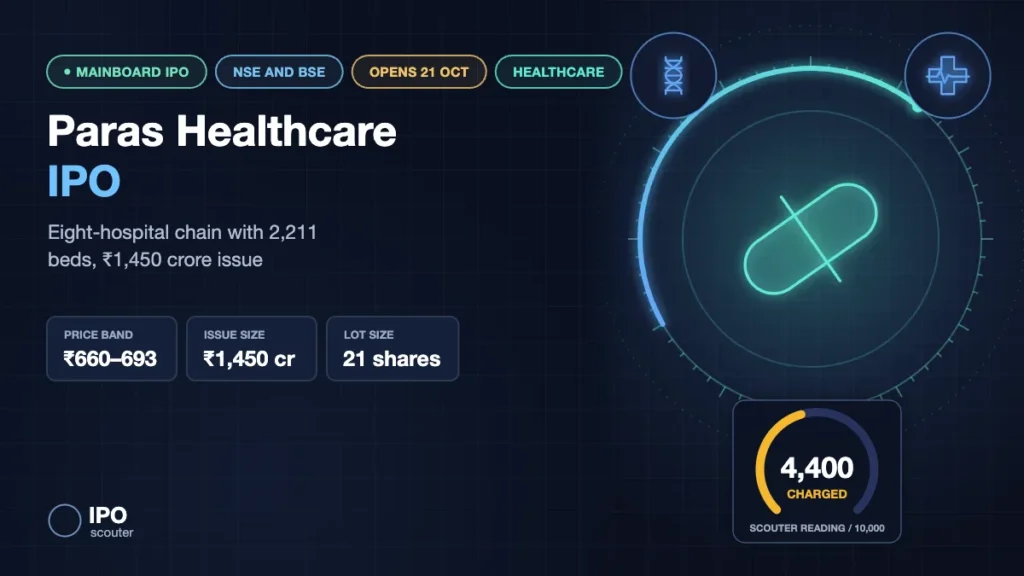
Paras Healthcare runs the Paras Health chain of hospitals, built around Gurugram and a set of smaller cities such as Patna, Panchkula, Ranchi, Udaipur, Kanpur, Darbhanga and Srinagar. Its ₹1,450 crore IPO, priced at ₹660 to ₹693 a share, opened on 21 October 2026 in the same window as Jio Platforms and was 0.34 times subscribed at the end of day 2, 22 October (consolidated NSE and BSE bid details). Retail investors had bid 1.31 times their portion; QIBs, who get 75% of the issue, had covered just 6% of theirs.
The company has just turned the corner. Revenue grew 24% in FY26 to ₹1,605.95 crore and EBITDA more than doubled to ₹335.58 crore, taking it to a ₹43.83 crore profit after losses in FY24 and FY25. But debt is high, at 3.5 times equity, and at the upper band the stock is priced at about 160 times FY26 earnings. The grey market premium has fallen to about ₹50 on 21 October, from ₹95 to ₹115 last week (unofficial).
Paras Healthcare IPO at a glance
| Detail | Paras Healthcare IPO |
|---|---|
| Issue size | ₹1,450 crore (2,09,23,520 shares) |
| Fresh issue | ₹500 crore (72,15,007 shares) |
| Offer for sale | ₹950 crore (1,37,08,513 shares) |
| Price band | ₹660 to ₹693 per share |
| Lot size | 21 shares (₹14,553 at the upper band) |
| Retail maximum | 13 lots, 273 shares (₹1,89,189) |
| sHNI minimum | 14 lots, 294 shares (₹2,03,742) |
| bHNI minimum | 69 lots, 1,449 shares (₹10,04,157) |
| Quota | QIB at least 75%, NII up to 15%, retail up to 10% of the net offer |
| Anchor round | ₹652.5 crore at ₹693 (top of the band), 19 October 2026 (reported) |
| Bidding dates | 21 to 23 October 2026 |
| Allotment | 26 October 2026 |
| Refund and demat credit | 27 October 2026 |
| Listing | 28 October 2026 on BSE and NSE |
| Promoter | Dr Dharminder Kumar Nagar (72.80% before the issue) |
| Lead managers | JM Financial, BofA Securities India and Nuvama Wealth Management |
| Registrar | MUFG Intime India |
Because Paras made losses in two of the last three years, it has to offer at least 75% of the net issue to QIBs, which leaves just 10% for retail investors. That makes allotment harder for small investors if demand is strong. The issue was cut from the ₹1,800 crore proposed in the draft papers.
Of the ₹500 crore fresh issue, ₹320.90 crore will repay or prepay company borrowings and ₹54.10 crore will go into a wholly owned subsidiary to repay its debt, with the rest for general corporate purposes. The ₹950 crore OFS goes to the promoter and investors who are selling.
What Paras Healthcare actually does
Founded in 2006 with its first hospital in Gurugram, Paras now runs eight hospitals with 2,211 beds, of which 1,502 were operational and 559 were ICU beds as of June 2026. Seven of the eight are NABH-accredited, and it had 1,084 doctors and 1,937 nurses on its rolls. About three-quarters of FY26 revenue came from cardiology, oncology, neurosciences, gastroenterology, orthopaedics and renal care.
Gurugram is the largest contributor at 31.8% of FY26 revenue, followed by Patna at 21.9% and Panchkula at 17.6%. The chain plans a 300-bed hospital in Gurugram by FY27 and a 500-bed hospital in Ludhiana by FY28, which would take total capacity to 3,011 beds.
Its payer mix is unusual: 41.3% of FY26 revenue came from government schemes and public sector companies, 33.9% from patients paying themselves and 24.8% from insurers. Government schemes tend to pay lower rates and pay more slowly, which shows up in receivables.
The numbers behind the business
These are the restated consolidated figures from the offer documents, in ₹ crore.
| ₹ crore | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue from operations | 1,129.04 | 1,294.06 | 1,605.95 |
| EBITDA | 154.41 | 156.46 | 335.58 |
| Profit before tax | 6.63 | -50.04 | 76.03 |
| Net profit | -15.33 | -57.98 | 43.83 |
| Operating cash flow | 92.48 | 86.19 | 163.51 |
| Return on net worth | -8.32% | -18.73% | 12.98% |
What these numbers tell us, in plain language:
- A sharp operating turnaround. EBITDA more than doubled in FY26 as bed occupancy rose from 50.8% to 61.8% and newer hospitals matured. Average revenue per occupied bed was ₹47,398 a day.
- Profit is still thin. Net profit of ₹43.83 crore is a 2.7% margin on revenue, after interest and depreciation on a capital-heavy business. One good year does not yet make a track record.
- Debt is the big issue. Debt to equity was 3.53 times in FY26, and fund-based borrowings were ₹939.47 crore at the end of August 2026. The fresh issue will cut that by about ₹375 crore, which should lift profit through lower interest costs.
- Receivables are climbing. Trade receivables rose from ₹156.31 crore in March 2024 to ₹349.57 crore in March 2026, reflecting the large share of government-scheme patients.
Paras Healthcare IPO subscription status
| Category | Day 1 (21 Oct, end of day) | Day 2 (22 Oct, end of day) |
|---|---|---|
| QIB (excluding anchor) | 0.00x | 0.06x |
| NII total | 0.08x | 0.25x |
| Big NII (above ₹10 lakh) | 0.05x | 0.22x |
| Small NII (₹2 to 10 lakh) | 0.14x | 0.31x |
| Retail | 0.69x | 1.31x |
| Total | 0.15x | 0.34x |
Paras opened in the shadow of Jio, which drew most of the day’s institutional money. Retail is the only category with meaningful bids so far, and because retail gets just 10% of this issue, the overall figure barely moves. QIBs, who get 75% of the offer, usually bid on the last day in mid-sized issues, so the day-3 QIB number is the one to watch. The ₹652.5 crore anchor book on 19 October (reported) already covers part of the institutional demand. Day 2 brought retail demand but little else: the retail portion was fully covered at 1.31 times, NIIs reached 0.25x and QIBs 0.06x, taking the total to 0.34x. We will add the final day-3 figures as the exchanges publish them.
Paras Healthcare IPO GMP today
Grey market trackers started quoting Paras on 14 October at about ₹75, and had it at ₹90 to ₹115 through 15 to 19 October, roughly 13% to 17% over the ₹693 upper band. The quote then halved: trackers showed about ₹50 on 20 October evening and again on the morning of 21 October as bidding opened, around 7% over the upper band, or about ₹1,050 on one lot of 21 shares (unofficial; calculated on the upper band). The fall came as Jio Platforms, opening the same day, pulled attention and money toward the larger issue.
How to check Paras Healthcare IPO allotment status
- Visit the MUFG Intime India allotment page, or the BSE or NSE allotment status page.
- Choose Paras Healthcare from the list.
- Enter your PAN, application number or DP and client ID.
- Submit to see the number of shares allotted.
The basis of allotment is expected on 26 October 2026, with refunds and demat credits on 27 October and listing on BSE and NSE on 28 October.
The listing outlook
Listed hospital stocks have been well rewarded in recent years, but the grey market has cooled on Paras: trackers quoted ₹95 to ₹115 last week and about ₹50 on 21 October (unofficial). Against that, the earnings multiple is very high because profit is only just positive, and most of the valuation rests on EBITDA growth from new beds and lower interest costs after the IPO.
Anchor result (reported, 19 October 2026): Paras Healthcare allotted 94,15,584 shares at ₹693, the top of the band, raising ₹652.5 crore, according to Business Line and Kotak Neo, which cite the exchange circulars. Investors named in those reports include SBI, HDFC, ICICI Prudential and Kotak mutual funds, the Abu Dhabi Investment Authority and BlackRock. That is about 45% of the ₹1,450 crore issue, the full 60% anchor share of the 75% QIB portion (calculated). Half the anchor shares are locked in for 30 days from allotment and the rest for 90 days. The next signal is QIB demand in the main book on the final day, 23 October.
What to weigh before you apply
Turnaround or a one-year jump?
FY26 was the first profitable year in three. Occupancy and EBITDA both improved sharply, which is what a maturing hospital chain should show, but investors need to see it repeated. The June 2026 quarter numbers in the RHP are worth checking for that reason.
Debt and government payers
A debt-to-equity ratio of 3.5 times is high for a hospital chain. Even after the IPO repays about ₹375 crore, borrowings stay significant, and the heavy reliance on government schemes slows cash collection.
A real regional franchise
Paras has built hospitals in cities where large chains are thin on the ground, such as Patna, Ranchi, Darbhanga and Srinagar. That gives it a first-mover position in markets with growing demand for specialist care, and it is one reason institutions are interested.
Strengths and risks
Strengths
- Eight hospitals and 2,211 beds across five states and one union territory
- Revenue up 24% and EBITDA up 114% in FY26
- Bed occupancy up from 50.8% to 61.8%
- Strong positions in under-served tier 2 and tier 3 cities
- ₹375 crore of the fresh issue goes to debt reduction
- Plans to reach 3,011 beds by March 2028
Risks
- Losses in FY24 and FY25; only one profitable year
- About 160 times FY26 diluted earnings at the upper band
- Debt to equity of 3.53 times
- 41% of revenue from government schemes and PSUs
- Receivables more than doubled in two years
- Retail quota capped at 10%, and ₹950 crore is an OFS
Scouter verdict: Paras Healthcare has built a genuine regional hospital franchise and FY26 shows the operating leverage of maturing beds. But it has only one profitable year, carries heavy debt, relies on slow-paying government schemes and is priced at about 160 times last year’s earnings. The grey market is positive; long-term investors are paying today for profits that are still a few years away. This is our own view, not investment advice.
Your chances of getting an allotment
- Retail investors get up to 10% of the net offer, about ₹145 crore or roughly 99,600 lots of 21 shares.
- Every successful retail applicant gets at least one lot, and lots are drawn at random if the retail book is oversubscribed.
- With a small retail quota and a positive GMP, the retail book could fill many times over, which would make the odds long.
- Bid at the cut-off price, and use separate family PANs rather than extra lots on one PAN.
What to watch from here
- QIB bids on the final day, 23 October, after the ₹652.5 crore anchor book
- Day by day subscription from 21 to 23 October, especially QIB
- Whether the GMP, about ₹50 on 21 October (unofficial), holds while Jio Platforms draws money in the same window
- Allotment on 26 October through MUFG Intime India
- After listing: occupancy, ARPOB and net debt in the half-year results
Paras Healthcare IPO: frequently asked questions
The price band is ₹660 to ₹693 per share, with a lot size of 21 shares. One lot costs ₹14,553 at the upper band, and the retail maximum of 13 lots costs ₹1,89,189.
At the end of day 2 (22 October 2026), the issue was 0.34 times subscribed: retail 1.31x, NIIs 0.25x and QIBs 0.06x (consolidated NSE and BSE bid details). Bidding closes on 23 October; allotment is expected on 26 October and listing on 28 October.
Grey market trackers quoted about ₹50 on the morning of 21 October 2026, around 7% over the ₹693 upper band, down from ₹95 to ₹115 a week earlier. GMP is unofficial, can change quickly and is not a forecast of the listing price.
Both. It is a ₹500 crore fresh issue and a ₹950 crore offer for sale. About ₹375 crore of the fresh money will repay borrowings at the company and a subsidiary.
Up to 10% of the net offer, with at least 75% for QIBs and up to 15% for NIIs. The small retail share is because the company made losses in FY24 and FY25.
Allotment is expected on 26 October 2026. Check it on the MUFG Intime India website or the BSE and NSE allotment pages using your PAN or application number.
Sources: MUFG Intime India (registrar) allotment page, BSE public issues, NSE IPO page, SEBI public issue filings (RHP), Kotak Neo IPO page (terms and financials), Kotak Neo, DRHP filing. Financials are from the company’s offer documents.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Data as of 16 October 2026; anchor result added 20 October 2026; subscription as of the end of day 2, 22 October 2026 (consolidated NSE and BSE bid details); GMP as of the morning of 21 October 2026.
On this page
Key valuation
| P/E (FY26 diluted EPS ₹4.34) | About 160x |
| EBITDA margin (FY26) | 20.9% |
| RoNW (FY26) | 12.98% |
| Debt to equity | 3.53x |
| Borrowings (Aug 2026) | ₹939.47 cr |
| Fresh issue | ₹500 cr |
| OFS | ₹950 cr |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Follow @ipoScouter on X