HD Fire Protect IPO: Listing Price, Listing Gains vs GMP and Review
Mumbai-based maker of sprinklers, deluge valves, foam and gas suppression systems, with UL and FM approved products, two plants in Maharashtra and exports to 49 countries in the June 2026 quarter.
A high quality, certified fire safety maker with strong margins and returns, but growth has slowed, the price is rich and not a rupee goes to the company.
Our own view, not investment advice.
Key numbers
FY26, restated
| Total income | ₹505.12 cr |
| Net profit | ₹116.79 cr |
| EBITDA margin | 30.8% |
| ROE | 30.2% |
| P/E at upper band | 40.7x |
| Promoter stake after IPO | 85% |
IPO timeline
Bidding closed on 15 October 2026 at 131.73x. Listed on 21 October 2026 at ₹335 on NSE and ₹334.40 on BSE, about 23.6% above the ₹271 issue price.
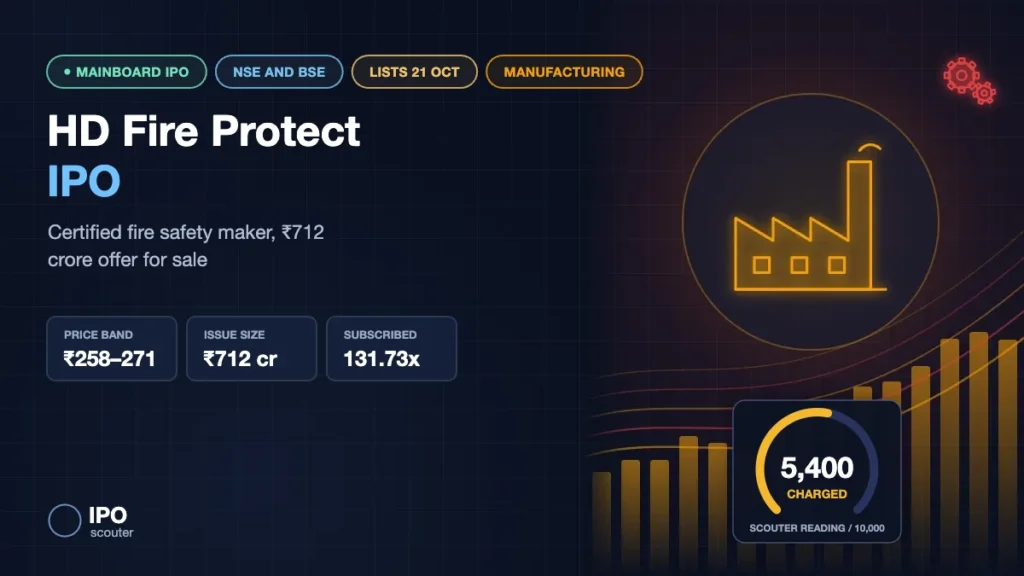
HD Fire Protect makes the equipment that puts out fires in refineries, power plants, data centres and large buildings: sprinklers, deluge valves, foam systems, monitors and gas suppression systems. Its ₹712.31 crore IPO, priced at ₹258 to ₹271 a share and 131.73 times subscribed, listed on 21 October 2026 at ₹335 on NSE, 23.6% above the ₹271 issue price, and closed its first day at ₹306.75, 13.2% above the issue price but 8.4% below its opening.
The business looks strong on paper. Net profit has grown from ₹87.92 crore in FY24 to ₹116.79 crore in FY26, return on equity was about 30% last year, and the company holds 21 UL listings and 87 FM approvals, the certifications that large industrial buyers insist on. But the whole issue is an offer for sale by the promoters, profit growth slowed to single digits in FY26, and at the upper band the stock is priced at about 41 times last year’s earnings.
How HD Fire Protect listed
| Detail | Value |
|---|---|
| Issue price | ₹271 |
| Listing price (NSE) | ₹335 (+23.6%) |
| Opening price (BSE) | ₹334.40 (+23.4%) |
| Day-1 range (NSE) | ₹301.50 to ₹340 |
| Day-1 close (NSE) | ₹306.75 (+13.2% vs issue) |
| Last GMP before listing | About ₹80 (unofficial, 15 Oct) |
| Final subscription | 131.73x overall, retail 30.55x |
HD Fire Protect opened at ₹335 on NSE and ₹334.40 on BSE on 21 October 2026, about 23.6% above the ₹271 issue price (exchange prices, as reported by Kotak Neo and 5paisa). The opening did not hold. The stock touched ₹340 early, fell to ₹302 within the first hour (5paisa) and did not get back near its opening. It closed at ₹306.75 on NSE, 13.2% above the issue price and 8.4% below where it opened, after a day low of ₹301.50 and a volume-weighted average of ₹314.23 (NSE quote, official closing price). By 10:56 AM about 2.66 crore shares had changed hands, roughly the entire 2.63 crore shares sold in the IPO (calculated: ₹712.31 crore ÷ ₹271).
For allottees, one lot of 55 shares bought at ₹271 was worth about ₹3,520 more at the opening price, before brokerage and taxes (calculated: ₹64 × 55), and about ₹1,970 more at the ₹306.75 close (calculated: ₹35.75 × 55). At ₹335 the company is valued at roughly ₹5,870 crore, or about 50 times FY26 profit of ₹116.79 crore, against 40.7 times at the issue price (calculated). With single-digit profit growth last year, that leaves the stock little room if the next few quarters disappoint.
How the subscription played out
| Category | Final subscription (15 Oct, 5:54 PM) |
|---|---|
| QIB (excluding anchor) | 256.65x |
| NII | 203.21x (big NII 236.17x, small NII 137.28x) |
| Retail | 30.55x |
| Employees | 23.61x |
| Total | 131.73x |
| Applications | 47,55,280 |
| Anchor book | ₹213.11 crore (78,64,008 shares at ₹271) |
HD Fire Protect closed its three-day issue on 15 October 2026 at 131.73 times, from 47.55 lakh applications. Demand built steadily: the book stood at 4.66x after day 1 and 11.59x after day 2, then jumped on the final day as institutions and wealthy investors piled in. QIBs bid 256.65 times their quota and NIIs 203.21 times, with the big NII segment at 236.17x. Retail investors bid 30.55 times.
Before bidding began, the company raised ₹213.11 crore from anchor investors, who were allotted 78,64,008 shares at ₹271. The basis of allotment was scheduled for 16 October. With retail at 30.55x, only about one retail application in 30 is likely to get the single 55-share lot, worth ₹14,905 at the upper band. Refunds and demat credits follow on 19 October, and the shares list on BSE and NSE on 21 October.
What the demand and the grey market point to
Grey market trackers put the premium at about ₹80 on 15 October, the last bidding day, after it touched about ₹88 on 13 and 14 October. That points to a listing near ₹351, roughly 30% above the issue price, or a gain of about ₹4,400 on one lot. Heavy QIB demand usually supports the opening, but a book this large also means much of the good news is already known, and the listing-day price will depend on the wider market mood on 21 October.
Our view on the business has not changed. HD Fire Protect is a certified niche maker with excellent margins and returns, priced at about 41 times FY26 earnings, and every rupee of the issue goes to the promoters. The subscription points to a good listing; the longer-term case still depends on growth picking up from the 6% profit increase of FY26.
HD Fire Protect IPO at a glance
| Detail | HD Fire Protect IPO |
|---|---|
| Issue size | ₹712.31 crore (2,62,84,500 shares, entirely offer for sale) |
| Price band | ₹258 to ₹271 per share (face value ₹5) |
| Lot size | 55 shares (₹14,905 at the upper band) |
| Retail maximum | 13 lots, 715 shares (₹1,93,765) |
| sHNI minimum | 14 lots, 770 shares (₹2,08,670) |
| bHNI minimum | 68 lots, 3,740 shares (₹10,13,540) |
| Quota | QIB up to 50%, retail at least 35%, NII at least 15% of the net offer |
| Employee discount | ₹25 per share |
| Bidding dates | 13 to 15 October 2026 |
| Allotment | 16 October 2026 |
| Refund and demat credit | 19 October 2026 |
| Listing | 21 October 2026 on BSE and NSE |
| Market cap at upper band | About ₹4,748.73 crore |
| Promoter holding | 100% before, 85% after |
| Lead managers | Ambit, Anand Rathi Advisors, IIFL Capital Services |
| Registrar | MUFG Intime India |
Because this is a pure offer for sale, the share count does not change and the company receives no money from the IPO. The two selling shareholders are promoters Kusum Harish Dharamshi, selling shares worth about ₹468.85 crore, and Harish Narshi Dharamshi, selling about ₹243.46 crore.
What HD Fire Protect actually does
HD Fire Protect Ltd was incorporated in April 1997 and is promoted by the Dharamshi and Ghotikar families. It designs and makes water, foam and gas based fire suppression equipment across eight product groups: sprinklers, alarm valves, deluge valves and systems, foam equipment, monitors and nozzles, water spray nozzles, custom engineered systems and gas suppression systems.
Its edge is certification. By its own account, the business became the first Indian maker to get a UL listing for deluge valves in 1996, before its incorporation as a company in April 1997, and it was the first Indian company to receive FM approval for a range of low expansion foam products. As of September 2026 it held 21 UL listings and 87 FM approvals. For refinery, oil and gas and export customers, buying uncertified equipment is simply not an option, so these approvals act as a real barrier to entry.
The company has two factories, in Jalgaon and Thane in Maharashtra, covering about 8.5 acres, along with its own fire test laboratory. It supplied 2,066 customers in FY26 and has exported to more than 90 countries since it started, including 49 in the June 2026 quarter. Its products have gone into the Samruddhi Mahamarg expressway, the Jamnagar refinery, the new Parliament building and Saudi Aramco’s Ras Tanura site. It had 279 permanent and 253 contract employees at the end of June 2026.
The numbers behind the business
Here are the restated figures from the offer documents, in ₹ crore.
| ₹ crore | FY24 | FY25 | FY26 | Q1 FY27 |
|---|---|---|---|---|
| Total income | 392.02 | 450.68 | 505.12 | 114.07 |
| EBITDA | 106.63 | 138.01 | 150.46 | 29.73 |
| Net profit | 87.92 | 109.72 | 116.79 | 23.87 |
| Total assets | 392.63 | 450.08 | 432.03 | 477.60 |
What these numbers tell us, in plain language:
- Profitable and consistent, but slowing. Net profit rose about 25% in FY25 and only about 6% in FY26. Total income grew about 12% last year. Revenue from operations grew at a 14.5% annual rate between FY24 and FY26, from about ₹373 crore to ₹489 crore.
- Margins are excellent for an industrial manufacturer. EBITDA margin was 30.8% and net margin 23.1% in FY26. That is what certified, engineered products can earn, but it also leaves less room for further margin gains.
- The June quarter was softer. Profit of ₹23.87 crore in Q1 FY27 works out to roughly ₹95 crore a year if annualised, below the FY26 figure. Fire protection sales are often lumpy around project deliveries, so one quarter is not conclusive, but it does not support a story of accelerating growth.
- High returns on a solid balance sheet. ROE was 30.2% and ROCE 40.3% in FY26. Net asset value was ₹21.45 a share at March 2026, which puts the IPO at about 12.6 times book.
HD Fire Protect IPO GMP vs listing price
The grey market premium was about ₹80 on 15 October, the last bidding day, after touching about ₹88 on 13 and 14 October (unofficial, grey-market trackers). That implied a listing near ₹351. The actual NSE opening of ₹335 came in about ₹16 lower: a ₹64 premium instead of ₹80, so the grey market overstated the listing gain by about a fifth (calculated). Even a 131x book did not get the stock to its GMP, and the slide after the open shows how much of the demand was short-term. GMP is an unregulated indicator and often differs from the listing price.
How to check HD Fire Protect IPO allotment status
- Head to the allotment section on the MUFG Intime India website. The BSE or NSE allotment status page works too.
- Select HD Fire Protect as the company.
- Provide your PAN, application number or demat (DP and client) ID.
- Submit, and the page will show how many shares were allotted to you, if any.
The basis of allotment was scheduled for 16 October 2026, followed by refunds and share credits on 19 October and the BSE and NSE listing on 21 October.
What we expected before listing
Before listing, the ₹80 GMP pointed to about ₹351, roughly 30% above the upper band. The anchor and QIB books both came in strong, with ₹213.11 crore from anchors and QIBs bidding 256.65 times their quota, so the main remaining variable is the general mood for new listings. Several mainboard debuts in early October, including Runwal Enterprises and German Green Steel, opened flat or slipped below their issue price within days, so the market is not rewarding every issue.
Over the longer term, the price will depend on whether HD Fire Protect can get revenue growth back into double digits. At 40 to 50 times earnings, the valuation already assumes a lot of steady compounding.
What to weigh after the listing
Nothing for the company, a lot for the promoters
This is a pure exit for two promoters, who will sell 15% of the company and take home about ₹712 crore. That is not unusual for a mature, cash generating business, and the promoter family will still own 85%. But it means the IPO adds no growth capital, and buyers should ask why the founders are selling now, at a time of slowing growth and a high multiple.
A premium price for single digit profit growth
At ₹271 the issue is valued at about 40.7 times FY26 earnings and about 49.7 times the annualised June quarter. There are few close listed Indian peers making certified fire suppression equipment at this scale, so there is no easy benchmark. Even so, a P/E above 40 usually needs growth well above the 6% profit increase the company reported last year.
Strong niche, real barriers
On the positive side, the UL and FM approvals, the 30 year export record and the list of marquee projects are hard to copy. Rising spending on refineries, data centres, airports and metro systems, together with tighter fire safety codes, should keep demand steady. This is a business we like at the right price.
Strengths and risks
Strengths
- 21 UL listings and 87 FM approvals, a real barrier for rivals
- Net profit of ₹116.79 crore in FY26 with a 23% net margin
- ROE of 30% and ROCE of 40% in FY26
- Exports to 49 countries in the June 2026 quarter and 2,066 customers in FY26
- Marquee projects across refineries, infrastructure and public buildings
- Promoters will still hold 85% after the issue
Risks
- Entirely an offer for sale; the company receives no money
- Profit grew only about 6% in FY26, and the June quarter was softer
- About 41 times FY26 earnings and 12.6 times book at the upper band
- Demand is tied to industrial and infrastructure project cycles
- Export earnings are exposed to currency and geopolitical risk
- A 30% GMP before opening raises the risk of disappointment
Scouter verdict: HD Fire Protect is a high quality, certified niche manufacturer with excellent margins and returns, and a 131.73x subscription with a GMP near ₹80 suggests a good listing. But growth slowed sharply in FY26, the June quarter was softer, the valuation is demanding and the entire issue is a promoter exit. Listing gains look likely on current signals; long term investors may get a better entry later if growth does not pick up. This is our own view, not investment advice.
How HD Fire Protect IPO allotment worked out
The retail portion was at least 35% of the net offer, roughly 1.67 lakh lots of 55 shares. Retail investors bid 30.55 times that, so only about one retail application in 30 won a lot (calculated). Under SEBI rules each successful retail applicant gets one lot and the rest are drawn by lottery, so bidding for more lots did not improve the odds. The registrar, MUFG Intime India, ran the allotment on 16 October, and shares were credited before the 21 October listing.
What to watch from here
- Quarterly results: whether revenue growth gets back to double digits and EBITDA margins stay above 28%
- Anchor lock-in: half of the 78.64 lakh anchor shares can be sold about 30 days after allotment (mid-November), the rest after 90 days (mid-January 2027)
- Any further selling by the promoter family, which still owns 85% after this offer for sale
- Where the price settles against the ₹271 issue price once listing-day trading fades
HD Fire Protect IPO: frequently asked questions
The price band is ₹258 to ₹271 per share, with a lot size of 55 shares. One lot costs ₹14,905 at the upper band, and the retail maximum of 13 lots costs ₹1,93,765.
The IPO was open from 13 to 15 October 2026 and closed 131.73 times subscribed, from 47.55 lakh applications. QIBs bid 256.65x, NIIs 203.21x and retail investors 30.55x. The company also raised ₹213.11 crore from anchor investors before the issue opened.
HD Fire Protect listed on 21 October 2026 at ₹335 on NSE and ₹334.40 on BSE, about 23.6% above the ₹271 issue price. The last grey market premium before listing was about ₹80 (unofficial), which had pointed to roughly ₹351.
It is entirely an offer for sale of ₹712.31 crore by promoters Kusum Harish Dharamshi and Harish Narshi Dharamshi. The company will not receive any money from the IPO.
HD Fire Protect makes fire protection equipment and systems, including sprinklers, deluge valves, foam and gas suppression systems. It holds 21 UL listings and 87 FM approvals and exports to dozens of countries.
The basis of allotment was scheduled for 16 October 2026. Check it on the MUFG Intime India website or the BSE and NSE allotment pages using your PAN or application number. With retail subscribed 30.55x, only about one retail application in 30 is likely to get a lot.
Sources: MUFG Intime India (registrar) allotment page, BSE public issues, NSE IPO page, BSE allotment status, NSE allotment status, SEBI public issue filings (RHP). Subscription and price data are from the exchanges; financials are from the company’s offer documents.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Subscription data as of the 15 October 2026 close; GMP as of 15 October 2026; listing and closing prices as of the 21 October 2026 close (NSE).
On this page
Key valuation
| P/E (FY26) | 40.7x |
| P/E (annualised Q1) | 49.7x |
| P/B | 12.6x |
| ROE | 30.2% |
| EBITDA margin | 30.8% |
| Net margin | 23.1% |
| Fresh money to company | Nil |
| Anchor money | ₹213.11 cr |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Follow @ipoScouter on X