Ravita Engineering Services IPO: Listing Price, Listing Gains vs GMP and Review
Navi Mumbai engineering firm that installs and maintains HVAC, chiller and cooling systems for commercial buildings, offshore oil rigs and platforms, and data centres.
Cheap on earnings and riding data centre demand, but revenue grew twentyfold in two years, which is too fast to take at face value without a longer record.
Our own view, not investment advice.
Key numbers
FY26, restated
| Total income | ₹277.82 cr |
| Net profit | ₹28.04 cr |
| EBITDA margin | 14.4% |
| ROE | 48.9% |
| P/E post-issue | 10.4x |
| Debt to equity | 0.19 |
IPO timeline
Bidding closed on 16 October 2026, 7.11 times subscribed. Allotment was finalised on 19 October, and the shares listed on NSE SME on 22 October at ₹112, closing day 1 at ₹113.70.
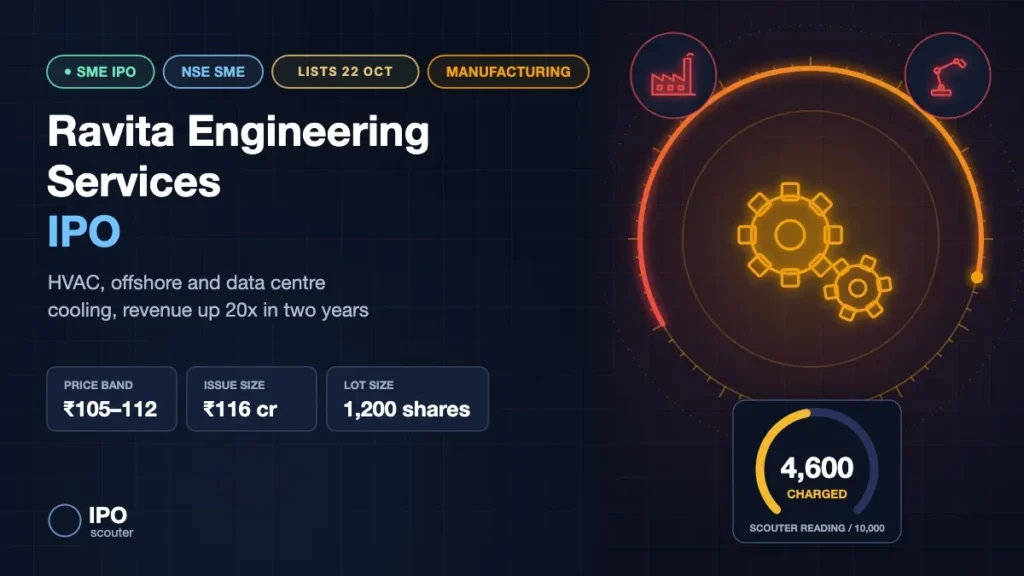
Ravita Engineering Services designs, installs and maintains heating, ventilation and air conditioning systems, chiller plants and other cooling equipment. Its clients range from offices and hotels to offshore oil rigs and, more recently, data centres. It is raising ₹116.05 crore on NSE SME, and its issue, open from 14 to 16 October 2026, closed 7.11 times subscribed. It listed on 22 October at ₹112, flat to the issue price, and closed its first day at ₹113.70.
On valuation it looks cheap, at about 10 to 11 times earnings. The catch is the speed of its growth: total income went from ₹13.53 crore in FY24 to ₹277.82 crore in FY26, a twentyfold jump in two years. A track record that short needs careful reading before you treat the low multiple as a bargain.
How Ravita Engineering Services listed
| Detail | Value |
|---|---|
| Issue price | ₹112 |
| Listing price (NSE SME) | ₹112 (flat) |
| Day-1 range (NSE SME) | ₹106.40 to ₹116.45 |
| Day-1 close (NSE SME) | ₹113.70 (+1.5% vs issue) |
| Last GMP before listing | About ₹2 (unofficial, 16 Oct) |
| Final subscription | 7.11x overall, QIB 13.21x |
Ravita Engineering Services listed on NSE SME on 22 October 2026 at ₹112, exactly its issue price (NSE quote). The flat start matched the grey market, which had pointed to only about ₹2 over the issue price. Trading was choppy: the stock fell to ₹106.40, its 5% lower price band for the day, then recovered to a high of ₹116.45 and closed at ₹113.70, 1.5% above the issue price (NSE official close; volume-weighted average ₹111.77). About 41.75 lakh shares changed hands, roughly 40% of the 1.04 crore shares sold in the IPO (calculated: ₹116.05 crore ÷ ₹112).
For allottees, the minimum retail holding of 2 lots (2,400 shares) bought for ₹2,68,800 was worth about ₹2,72,880 at the close, a gain of about ₹4,080 before costs (calculated). Shares trade in lots of 1,200 on NSE SME, so selling means selling whole lots.
Final subscription and allotment update
| Category | Day 1 (14 Oct) | Day 2 (15 Oct) | Final (16 Oct, 5:54 PM) |
|---|---|---|---|
| QIB (excluding anchor) | 1.05x | 1.33x | 13.21x |
| NII | 1.69x | 2.57x | 7.42x (big NII 9.11x, small NII 4.06x) |
| Individual investors | 0.95x | 1.53x | 3.50x |
| Total | 1.14x | 1.70x | 7.11x |
Ravita Engineering’s issue opened on 14 October 2026 and closed on 16 October at 7.11 times, with bids for about 4.90 crore shares against 68.92 lakh on offer. The book had been a steady 1.14x after day 1 and 1.70x after day 2; the final day brought the big jump, led by QIBs at 13.21 times and big NIIs at 9.11 times. Individual investors finished at 3.50 times. (Our preview had listed 13 to 15 October; the final timetable ran a day later.)
Before bidding began, the company raised ₹33.02 crore from anchor investors, who took 29,48,400 shares at ₹112, about 28% of the issue. Half of the anchor shares are locked in for 30 days and the rest for 90 days. The basis of allotment was scheduled for 19 October through MUFG Intime India, with refunds and demat credits on 21 October and listing on NSE SME on 22 October.
Late institutional demand, a quiet grey market
A 7x book is healthy for a ₹116 crore SME issue, and the late QIB demand is a better sign than retail froth would have been. The grey market has not followed, though: trackers still quoted the premium at about ₹2 after the close, under 2% over the ₹112 upper band, which points to a listing near ₹114. At about 10 times earnings the price is undemanding, but a two-year record of rapid growth is what the market seems unwilling to pay up for yet.
Ravita Engineering Services IPO at a glance
| Detail | Ravita Engineering Services IPO |
|---|---|
| Issue size | ₹116.05 crore (1,03,62,000 shares, entirely fresh issue) |
| Price band | ₹105 to ₹112 per share (face value ₹5) |
| Lot size | 1,200 shares |
| Individual investor application | 2 lots, 2,400 shares (₹2,68,800) |
| HNI minimum | 3 lots, 3,600 shares (₹4,03,200) |
| Quota | QIB up to 50%, retail at least 35%, NII at least 15% of the net issue |
| Anchor round | ₹33.02 crore, 29,48,400 shares at ₹112 (13 Oct) |
| Market maker portion | 5,22,000 shares, Pace Stock Broking Services |
| Bidding dates | 14 to 16 October 2026 |
| Allotment | 19 October 2026 |
| Refund and demat credit | 21 October 2026 |
| Listing | 22 October 2026 on NSE SME |
| Market cap at upper band | About ₹422 crore post-issue |
| Promoter holding | 73.74% before, 53.46% after |
| Lead manager | Vivro Financial Services |
| Registrar | MUFG Intime India |
Individual investors in SME issues must apply for at least two lots, which here is 2,400 shares or ₹2,68,800 at the upper band. Promoter holding will fall to about 53% after the issue, lower than most SME listings.
What Ravita Engineering Services actually does
Ravita Engineering Services Ltd was incorporated in December 2007 and is based in CBD Belapur, Navi Mumbai. It is led by chairman Vibhoar Agrawal and managing director and CEO Sunildutt Narayan Goswami, and its promoters are Vibhoar Agrawal, Rachita Agrawal and Starwings Realtors.
The company works on a turnkey basis, which it calls EPIC: engineering, procurement, installation and commissioning of HVAC systems, central air conditioning, air flow systems, chiller plants and industrial compressors. It also runs operations and maintenance contracts, both for systems it installed and for equipment put in by others.
It reports three segments. Onshore covers commercial, hospitality, corporate and industrial buildings. Offshore covers oil rigs and platforms, where it has worked on 6 rigs and 16 associated platforms over the last three years. Data Center is the newest and covers cooling, chiller and mechanical utility upkeep for data centres; the company says it has won data centre infrastructure work orders worth about ₹120 crore in Maharashtra. It had 399 permanent employees at the end of June 2026, 369 of them at sites.
Of the IPO money, ₹70 crore will go to working capital and ₹25.53 crore to buying heavy equipment, with the rest for general corporate purposes.
The numbers behind the business
These are the restated figures from the offer documents, in ₹ crore.
| ₹ crore | FY24 | FY25 | FY26 | Q1 FY27 |
|---|---|---|---|---|
| Total income | 13.53 | 109.30 | 277.82 | 97.45 |
| EBITDA | 2.86 | 15.65 | 40.05 | 14.04 |
| Net profit | 1.51 | 11.83 | 28.04 | 10.13 |
| Net worth | 3.30 | 15.13 | 99.56 | 109.69 |
| Borrowings | 3.52 | 23.11 | 19.21 | 30.88 |
| Total assets | 9.08 | 58.24 | 162.97 | 207.34 |
What these numbers tell us, in plain language:
- Explosive growth from a very small base. Income rose about eight times in FY25 and two and a half times in FY26. The June 2026 quarter alone, at ₹97.45 crore, was close to all of FY25. Growth like this usually comes from a handful of large contracts, which makes it harder to predict.
- Margins are steady. EBITDA margin was about 14.4% and net margin about 10.1% in FY26, and both held at similar levels in the June quarter. That consistency is a good sign for a services contractor.
- Net worth jumped faster than profit. Net worth rose from ₹15.13 crore to ₹99.56 crore in FY26 while profit was ₹28.04 crore, which points to fresh equity raised during the year before the IPO. Investors should check the RHP for who bought those shares and at what price.
- Debt is modest but working capital is heavy. Borrowings were ₹30.88 crore in June 2026 and debt to equity about 0.28. The decision to put ₹70 crore of the IPO into working capital shows how much cash a fast growing contractor ties up in receivables.
Ravita Engineering Services IPO GMP: the story so far
The grey market had not started quoting Ravita Engineering as of 8 October 2026, which is common for SME issues a week before they open. Once bidding began, trackers quoted a premium of about ₹2 on 15 and 16 October, under 2% over the upper band, and the figure did not move much despite the strong final day. GMP is unofficial and often changes sharply around allotment and listing.
How to check Ravita Engineering Services IPO allotment status
- Visit the registrar, MUFG Intime India, or the NSE allotment page.
- Find Ravita Engineering Services among the listed issues and select it.
- Fill in your PAN or application number, or your DP and client ID.
- Press submit and check the shares allotted figure.
Allotment is scheduled for 19 October 2026, with refunds and demat credits on 21 October. The shares should start trading on NSE SME on 22 October.
Ravita Engineering Services IPO listing date and listing price
The shares listed on NSE SME on 22 October 2026, as scheduled. Before listing, a 7.11x book alongside a GMP of only about ₹2 pointed to a listing close to the issue price, and that is what happened: ₹112 at the open and ₹113.70 at the close. Over the longer term, the stock will depend on whether the company can show that its sharp jump in revenue is repeatable.
What to weigh after the listing
Growth that needs a longer record
A twentyfold rise in income in two years can be real, especially if the company has won a few large offshore or data centre contracts. It can also reverse just as fast if those contracts end. The RHP’s customer concentration and order book disclosures are the most important pages to read before applying.
A genuine data centre angle
India’s data centre build out needs cooling and chiller maintenance, and Ravita already has work orders in this area. That is a structural tailwind that most SME contractors do not have, and it supports a higher multiple if the segment keeps growing.
Lower promoter ownership
After the issue the promoters will own about 53%. That is still a majority, but it is lower than many SME companies, and combined with the pre-IPO equity raise it means a larger part of the free float may be held by investors who could sell after listing.
Ravita Engineering Services IPO review: strengths and risks
Strengths
- Income up from ₹13.53 crore in FY24 to ₹277.82 crore in FY26
- Steady margins: EBITDA about 14%, net profit about 10%
- About 10 to 11 times earnings at the upper band
- Presence in offshore oil and gas and in data centre cooling
- Entirely fresh issue; no promoter is selling
- Low debt, debt to equity about 0.2 to 0.3
Risks
- Very short record of scale; growth may depend on a few contracts
- Large working capital needs, ₹70 crore of the issue goes there
- Equity raised before the IPO lifted net worth sharply
- Promoter holding falls to about 53%
- GMP of only about ₹2, under 2%
- SME stock: high ticket size of ₹2.69 lakh and lower liquidity
Scouter verdict: Ravita Engineering is growing very fast, earns steady margins and is priced at only about 10 times earnings, with a real foothold in data centre cooling. Against that, its scale is barely two years old, it needs a lot of working capital and promoters will own just over half the company. Anchors put in ₹33.02 crore and QIBs have covered their quota, but with a GMP of about ₹2 the case rests on the business rather than a listing gain. This is our own view, not investment advice.
Your chances of getting an allotment
- The retail portion is at least 35% of the net issue of 98,40,000 shares, about 34.4 lakh shares. At 2,400 shares per application, roughly 1,435 retail applications can be filled in full.
- Individual investors bid 3.50 times their portion, so roughly one valid application in three or four should get the two-lot minimum.
- When demand for the retail portion is higher than the shares available, the registrar runs a random draw and every winner gets the two lot minimum.
- Bidding for more lots on one PAN does not raise your chances, because the draw counts applications. Applications from family members with their own PANs do.
What to watch from here
- The basis of allotment on 19 October
- Refunds and demat credits on 21 October
- Whether the GMP moves off ₹2 before listing
- Listing on NSE SME on 22 October
- After listing: data centre order wins and receivable days in the half-year results
Ravita Engineering Services IPO: frequently asked questions
The price band is ₹105 to ₹112 per share with a lot size of 1,200 shares. Individual investors must apply for 2 lots, 2,400 shares, which costs ₹2,68,800 at the upper band.
Allotment was scheduled for 19 October 2026, with refunds and demat credits on 21 October. The IPO opened on 14 October and closed on 16 October 2026, 7.11 times subscribed.
Go to the registrar, MUFG Intime India, or the NSE allotment page, select Ravita Engineering Services, enter your PAN, application number or DP and client ID, and submit to see the shares allotted. Allotment was scheduled for 19 October 2026.
The last grey market premium we tracked was about ₹2 on 16 October 2026, under 2% over the ₹112 upper band. The shares then listed flat at ₹112 on 22 October, so the muted grey market signal proved broadly right. GMP is unofficial and no longer matters now that the shares trade.
Ravita Engineering Services listed on NSE SME on 22 October 2026 at ₹112, flat to the issue price. It traded between ₹106.40 and ₹116.45 and closed day 1 at ₹113.70, 1.5% above the issue price (NSE).
None at the open: the shares listed at ₹112, the same as the issue price. At the ₹113.70 day-1 close, the minimum retail holding of 2,400 shares bought for ₹2,68,800 was worth ₹2,72,880, a gain of about ₹4,080 before costs (calculated from NSE prices).
Strengths: income grew from ₹13.53 crore in FY24 to ₹277.82 crore in FY26, EBITDA margin is about 14%, the price is about 10 to 11 times earnings, the issue is entirely fresh and debt is low. Risks: a very short record at this scale, heavy working capital needs, promoter holding falling to about 53% and lower SME liquidity. This is not a buy or sell call.
It installs and maintains HVAC, chiller and cooling systems on a turnkey basis for commercial buildings, offshore oil rigs and platforms, and data centres.
About ₹70 crore will fund working capital and ₹25.53 crore will buy heavy equipment, with the balance for general corporate purposes. The entire issue is fresh capital.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Subscription data as of the 15 October 2026 close, with a late-morning check on 16 October; GMP as of 16 October 2026.
On this page
Key valuation
| P/E (FY26) | 10.9x |
| P/E (annualised Q1) | 10.4x |
| P/B | 3.1x |
| ROE (FY26) | 48.9% |
| EBITDA margin | 14.4% |
| Debt to equity | 0.19 |
| Promoter holding after | 53.46% |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Follow @ipoScouter on X