Fusion CX IPO: Listing Price, Listing Gains vs GMP and Review
Kolkata-based customer experience and business process company with 40 delivery centres in 13 countries, 208 clients and an AI products arm, Omind Technologies.
Fast profit growth, a 30% ROE and a fair multiple of about 25 times FY26 earnings, and QIBs arrived on the final day to take the book to 4.68 times, though the grey market premium is modest.
Our own view, not investment advice.
Key numbers
FY26, restated consolidated
| Total income | ₹1,851.83 cr |
| EBITDA | ₹329.87 cr |
| Net profit | ₹169.84 cr |
| ROE | 30.3% |
| Debt to equity | 0.53x |
| Anchor book | ₹315.90 cr |
IPO timeline
Bidding closed on 16 October 2026, 4.68 times subscribed. Allotment was finalised on 19 October, and the shares listed on BSE and NSE on 22 October, opening at ₹305 on NSE and closing day 1 at ₹289.65.
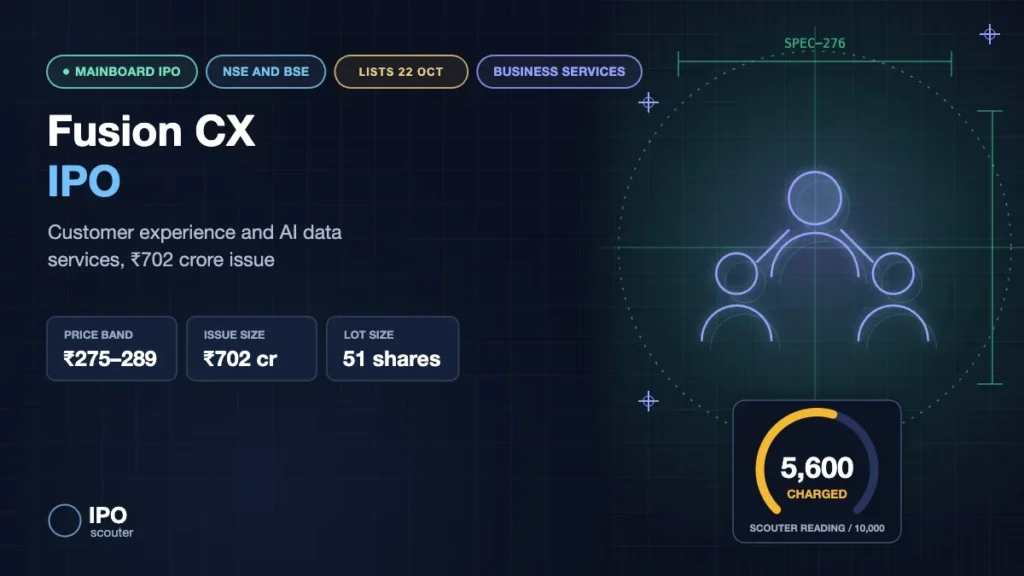
Fusion CX runs contact centres and back-office operations for companies in telecom, healthcare, banking, retail and travel, handling customer calls, chats and emails in 28 languages. The Kolkata company also has a growing AI data business and an AI products arm, Omind. Its ₹702 crore IPO opened on 14 October 2026 at ₹275 to ₹289 a share and closed on 16 October, 4.68 times subscribed. It listed on 22 October at ₹305 on NSE, 5.5% above the issue price, but closed its first day at ₹289.65, barely above it.
The numbers look good: total income rose 37% to ₹1,851.83 crore in FY26 and profit more than doubled to ₹169.84 crore. At the upper band the post-issue valuation is about ₹4,172 crore, roughly 25 times FY26 earnings. QIBs, who had barely bid by day 2, came in on the last day at 4.21 times, while retail investors finished at 5.99 times. The grey market premium, about ₹36 on opening day, settled at around ₹10 to ₹12 after the close, according to trackers.
How Fusion CX listed
| Detail | Value |
|---|---|
| Issue price | ₹289 |
| Listing price (NSE) | ₹305 (+5.5%) |
| Opening price (BSE) | ₹292 (+1.0%, reported) |
| Day-1 range (NSE) | ₹284.35 to ₹312.95 |
| Day-1 close (NSE) | ₹289.65 (+0.2% vs issue) |
| Last GMP before listing | About ₹10 to ₹12 (unofficial, 17 Oct) |
| Final subscription | 4.68x overall, retail 5.99x |
Fusion CX opened at ₹305 on NSE on 22 October 2026, 5.5% above the ₹289 issue price and slightly ahead of the ₹10 to ₹12 grey market premium (NSE quote). On BSE it opened lower, at ₹292 (+1.0%, as reported by Equentis). The early gain did not last. After a high of ₹312.95 the stock slid through the session, touched ₹284.35 and closed at ₹289.65 on NSE, just 0.2% above the issue price and 5.0% below its opening (NSE official close; volume-weighted average ₹301.56). About 1.80 crore shares traded on NSE alone, roughly three quarters of the 2.43 crore shares sold in the IPO (calculated: ₹702 crore ÷ ₹289).
For allottees, one lot of 51 shares bought for ₹14,739 was worth about ₹14,772 at the close, a gain of about ₹33 before costs, against ₹816 at the opening price (calculated). At ₹289.65 the company was valued at about ₹4,181 crore (NSE).
Final subscription and allotment update
| Category | Final subscription (16 Oct, 5:54 PM) |
|---|---|
| QIB (excluding anchor) | 4.21x |
| NII | 4.73x (big NII 4.72x, small NII 4.75x) |
| Retail | 5.99x |
| Total | 4.68x |
| Applications | 2,63,439 |
| Anchor book | ₹315.90 crore (1,09,30,795 shares at ₹289) |
Fusion CX closed its three-day issue on 16 October 2026 at 4.68 times, from 2.63 lakh applications. The book had stood at just 1.16 times after day 2, with QIBs at 0.05 times, and the final day changed the picture: QIBs ended at 4.21 times their quota and NIIs at 4.73 times, with big and small NII almost level. Retail investors, who get only 10% of the issue, bid 5.99 times.
The basis of allotment was scheduled for 19 October through KFin Technologies. With retail at 5.99x, roughly one retail application in six is likely to get the single 51-share lot, worth ₹14,739 at the upper band. Refunds and demat credits follow on 21 October, and the shares are scheduled to list on BSE and NSE on 22 October.
Before bidding opened, the company raised ₹315.90 crore from anchor investors on 13 October, covering 1,09,30,795 shares, or 45% of the issue. Half of those shares are locked in until 18 November and the rest until 17 January 2027.
A premium that has faded
The grey market premium was about ₹36.50 on 14 October, the opening day, about 12.6% over the upper band. It slid to single digits during the final afternoon and, after the close, trackers quoted around ₹10 to ₹12 on 16 and 17 October. At ₹12 the signal is a modest listing around ₹301, about 4% over the issue price, or roughly ₹612 on one 51-share lot. GMP is unofficial and often moves sharply before listing.
Fusion CX IPO at a glance
| Detail | Fusion CX IPO |
|---|---|
| Issue size | ₹702 crore (2,42,90,657 shares) |
| Fresh issue | ₹500 crore (1,73,01,038 shares) |
| Offer for sale | ₹202 crore (69,89,619 shares) by promoter companies P.N.S. Business and Rasish Consultants, ₹101 crore each |
| Price band | ₹275 to ₹289 per share (face value ₹1) |
| Lot size | 51 shares (₹14,739 at the upper band) |
| Retail maximum | 13 lots, 663 shares (₹1,91,607) |
| sHNI minimum | 14 lots, 714 shares (₹2,06,346) |
| bHNI minimum | 68 lots, 3,468 shares (₹10,02,252) |
| Quota | QIB 75% (including anchor 45%), NII 15%, retail 10% |
| Anchor round | ₹315.90 crore (13 Oct) |
| Bidding dates | 14 to 16 October 2026 |
| Allotment | 19 October 2026 |
| Refund and demat credit | 21 October 2026 |
| Listing | 22 October 2026 on BSE and NSE |
| Market cap at upper band | ₹4,172.01 crore post-issue |
| Promoter holding | 99.03% before, 81.82% after |
| Lead managers | Nuvama Wealth Management, IIFL Capital Services and Motilal Oswal |
| Registrar | KFin Technologies |
The promoters are Pankaj Dhanuka and Kishore Saraogi, along with their holding companies P.N.S. Business and Rasish Consultants, which are selling ₹101 crore of shares each. Of the ₹500 crore fresh issue, ₹275.70 crore will repay borrowings at the company and its subsidiaries, ₹61.15 crore will go into Omind Technologies to upgrade its Arya and MindVoice AI tools, and the rest is for acquisitions and general corporate purposes.
What Fusion CX actually does
Fusion CX was incorporated in 2004. It provides customer support over voice, email, chat, social media and messaging, and back-office processing, for 208 customers including 22 Fortune 1000 companies. It ran 40 delivery centres across 13 countries as of June 2026 and offers support in 28 languages.
Two newer lines are growing alongside the core business. Its AI data services cover data capture and annotation, image and video labelling and robotic teleoperations, the kind of work used to train AI models. Its subsidiary Omind builds AI products for marketing, conversational support, quality checks and workforce management.
The numbers behind the business
These are the restated consolidated figures from the offer documents, in ₹ crore.
| ₹ crore | FY24 | FY25 | FY26 | Q1 FY27 |
|---|---|---|---|---|
| Total income | 1,021.53 | 1,352.03 | 1,851.83 | 503.85 |
| EBITDA | 104.62 | 197.78 | 329.87 | 95.09 |
| Net profit | 36.26 | 74.31 | 169.84 | 55.70 |
| Net worth | 270.15 | 354.58 | 552.46 | 610.84 |
| Total borrowings | 210.61 | 306.73 | 266.86 | 238.13 |
What these numbers tell us, in plain language:
- Strong growth. Total income grew 32% in FY25 and 37% in FY26, and the June 2026 quarter was up about 28% on the same quarter a year earlier.
- Margins are rising. EBITDA margin improved from about 10% in FY24 to 19.5% in FY26 and 20% in the June quarter, helped by higher-value AI data and digital work.
- High returns. ROE was 30.3% and ROCE 71.6% in FY26, very high for a services business, though ROE will fall as the IPO money adds to equity.
- Debt is coming down. Borrowings fell from ₹306.73 crore in FY25 to ₹238.13 crore in June 2026, and the IPO will repay ₹275.70 crore, leaving the company close to debt free.
Fusion CX IPO GMP: the story so far
The grey market started positive, at about ₹36.50 on 14 October, then weakened as QIB bidding failed to pick up, briefly falling to around ₹5 on the final afternoon. After QIBs came in late, trackers quoted around ₹10 to ₹12 on 16 and 17 October, which points to a listing a little above the ₹289 issue price.
How to check Fusion CX IPO allotment status
- Open the KFin Technologies IPO allotment page, or the BSE or NSE allotment status page.
- Select Fusion CX from the list of issues.
- Enter your PAN, application number or DP and client ID.
- Submit to see how many shares were allotted.
The basis of allotment was scheduled for 19 October 2026. Refunds and demat credits follow on 21 October, and the shares list on BSE and NSE on 22 October.
Fusion CX IPO listing date and listing price
Fusion CX listed on BSE and NSE on 22 October 2026, as scheduled. Before listing, a 4.68 times book and a GMP of about ₹10 to ₹12 pointed to a modest premium. The shares did open about 5.5% higher on NSE, but gave almost all of it back by the close. On valuation, about 25 times FY26 earnings at the issue price is reasonable for a business growing profit this fast, and the first-day close leaves that multiple roughly unchanged.
Over the long term, the share price will depend on whether the AI data and Omind businesses keep lifting margins, and on how well Fusion CX holds its pricing in a competitive outsourcing market.
What to weigh after the listing
A fair price for strong growth
Profit has more than quadrupled in two years and returns are high. At about 25 times FY26 earnings the price looks fair rather than stretched, and most of the issue is fresh money that cuts debt.
Institutional demand came late
QIBs had bid only 0.05 times their quota by the end of day 2 and finished at 4.21 times. Institutions get 75% of this issue, so that late demand matters, but 4.21 times is modest next to the 100x-plus QIB books seen on hot issues, and listing gains may be limited.
A competitive industry
Customer experience outsourcing is crowded and price-sensitive, and generative AI could change how much human support companies buy. Fusion CX is trying to get ahead of that through Omind and AI data work, but it is a risk worth weighing.
Fusion CX IPO review: strengths and risks
Strengths
- Net profit up from ₹36 crore in FY24 to ₹170 crore in FY26
- EBITDA margin nearly doubled to about 20%
- ROE of 30% in FY26
- 40 delivery centres in 13 countries and 208 clients
- Most of the issue is fresh capital to repay debt
- About 25 times FY26 earnings, lower than many new listings
Risks
- QIB demand came only on the last day (4.21x)
- GMP down from ₹36.50 to about ₹10 to ₹12
- Retail quota capped at 10%
- Competitive, price-sensitive outsourcing market
- AI could reduce demand for human-led support
- Promoter companies are selling ₹202 crore of shares
Scouter verdict: Fusion CX has strong growth, rising margins and high returns, and at about 25 times earnings the price is fair for that record. The concern is demand: QIBs had barely bid going into the last day and the grey market premium has faded to almost nothing. The business case is better than the listing signal; investors who like it for the long term may also get a chance to buy after listing. This is our own view, not investment advice.
Your chances of getting an allotment
- Retail investors get 10% of the issue, 24,29,066 shares or about 47,600 lots of 51 shares.
- Retail bid 5.99 times its quota, so lots will be drawn at random.
- At 5.99 times, roughly one valid retail application in six should get a lot.
- Bidding for more lots on one PAN does not help in the lottery. Separate family PANs do.
What to watch from here
- The basis of allotment on 19 October
- Whether the GMP holds around ₹10 to ₹12 before listing
- Refunds and demat credits on 21 October (KFin Technologies is the registrar)
- Listing on BSE and NSE on 22 October
- After listing: margin trends and growth in AI data services and Omind
Fusion CX IPO: frequently asked questions
The price band is ₹275 to ₹289 per share, with a lot size of 51 shares. One lot costs ₹14,739 at the upper band, and the retail maximum of 13 lots costs ₹1,91,607.
The basis of allotment was scheduled for 19 October 2026, with refunds and demat credits on 21 October. The IPO opened on 14 October and closed on 16 October 2026, 4.68 times subscribed.
Go to the registrar, KFin Technologies, or the BSE or NSE allotment page, select Fusion CX, enter your PAN, application number or DP and client ID, and submit to see the shares allotted. Allotment was scheduled for 19 October 2026.
The issue closed 4.68 times subscribed on 16 October 2026. QIBs bid 4.21x, NIIs 4.73x and retail investors 5.99x, from 2.63 lakh applications. Anchor investors put in ₹315.90 crore before the issue opened.
Trackers quoted the grey market premium at about ₹10 to ₹12 on 16 and 17 October 2026, down from about ₹36.50 on the opening day. The NSE listing on 22 October came in ₹16 above the ₹289 issue price, slightly ahead of that GMP. GMP is unofficial and no longer matters now that the shares trade.
Fusion CX listed on 22 October 2026 at ₹305 on NSE (+5.5%) and ₹292 on BSE (+1.0%, reported) against the ₹289 issue price. It traded between ₹284.35 and ₹312.95 on NSE and closed day 1 at ₹289.65, 0.2% above the issue price.
It depended on when you sold. At the ₹305 NSE open, one lot of 51 shares bought for ₹14,739 was worth ₹15,555, a gain of ₹816 before costs. At the ₹289.65 day-1 close the gain was about ₹33 (calculated from NSE prices).
Strengths: net profit rose from ₹36 crore in FY24 to ₹170 crore in FY26, EBITDA margin is about 20%, ROE was 30% in FY26, most of the issue is fresh capital to repay debt and the price is about 25 times FY26 earnings. Risks: QIB demand came only on the last day, the GMP faded from about ₹36.50 to ₹10 to ₹12, outsourcing is competitive and AI could reduce demand for human-led support. This is not a buy or sell call.
Both. It is a ₹500 crore fresh issue and a ₹202 crore offer for sale by promoter companies P.N.S. Business and Rasish Consultants. ₹275.70 crore of the fresh money will repay debt.
Disclaimer: This article is for information and education only and is not investment advice. GMP is unofficial and data may differ between sources. Read the RHP and consult a SEBI-registered adviser before investing. Subscription data as of the 15 October 2026 close; GMP as of 16 October 2026, afternoon.
On this page
Key valuation
| Market cap (post-issue) | ₹4,172 cr |
| P/E (FY26, post-issue) | About 25x |
| P/E (annualised Q1) | 18.7x |
| P/B (Jun 2026) | 5.98x |
| ROE (FY26) | 30.3% |
| EBITDA margin (FY26) | 19.5% |
| Anchor money | ₹315.90 cr |
IPO alerts
Get GMP moves, subscription updates and allotment links the moment they change.
Follow @ipoScouter on X